

In case you missed it, here is the previous article:

Dear Merchants,
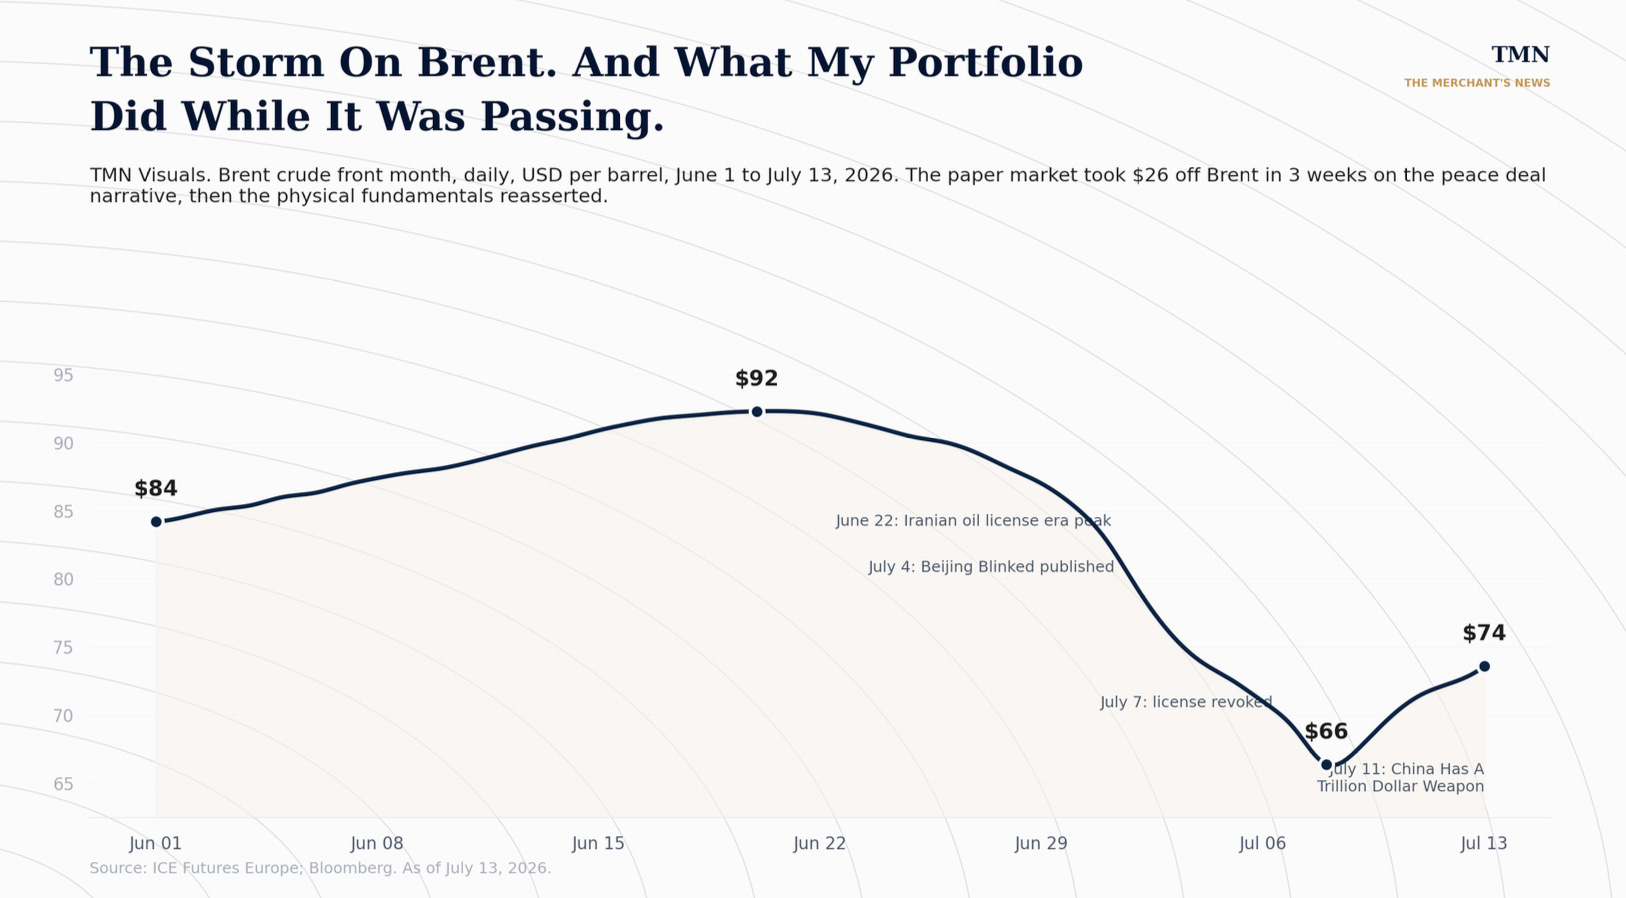
3 weeks ago, crude was trading firmly.
My portfolio was long 13 names across LNG, midstream, integrateds, upstream, oilfield services and 1 AI power play, and I had just published the strongest flagship of my year telling you the Chinese buyer strike would end in weeks. Then something uncomfortable happened.
Brent fell hard in a matter of days.
The war premium evaporated.
The peace deal narrative took over and I had to sit down and ask myself a question I did not want to answer.
Was I wrong? Was the thesis broken?
I spent the last weeks doing nothing but stress testing that question, across 5 articles and every position I hold.
Here is the answer.
12 of my 13 positions are still green.
Average return across the portfolio is roughly 9%. My biggest winner is up 33% since entry.
My only loser is down 16%, and I had already flagged it as a watch bench a month ago and trimmed the position before the deeper drop. Oil is rising again this week as the physical fundamentals reassert themselves.
The portfolio did not just survive the storm. It came out of it validated, and the trim decisions I made along the way protected the downside.
The 3 Weeks I Did Nothing But Research
The 5 major articles I published in the last 4 weeks were not scattered topics. They were 5 different lenses on the same question: is the resource war regime real, or is it just a war premium that fades?
June 24, Trump’s Two Front Squeeze, tested whether the Trump administration would keep pushing crude down through SPR draws and the Iranian license.
Answer: yes, for 60 days.
Then the license got revoked on July 7.
The test held.
July 4, Who Survives Europe’s Energy Crisis, tested whether European LNG demand is structural or cyclical.
Answer: structural.
Germany at 92% US LNG dependency confirms the buyer is locked in.
July 4, Beijing Blinked, tested whether the Chinese buyer strike would break the range or just reset it.
Answer: reset.
The buyer came back, Saudi took an $11 OSP cut to force it, but the physical deficit was smaller than my June 11 model implied because dark Hormuz transits filled the gap.
July 9, When Did The War Move Inside The Refineries, tested whether the peace deal actually stops the resource war or just moves it.
Answer: it moves it.
The war is now inside refineries.
July 11, China Has A Trillion Dollar Weapon, tested whether the American answer, LNG dominance, is real or theoretical.
Answer: real.
The mechanism is documented.
The bottom line after 3 weeks: the thesis held.
Not the exact magnitude of my June 11 base case, which overstated the physical deficit. But the direction, the regime, and the structural answer all held.
Why The Paper Market Can Move Oil But Not The Fundamentals Underneath
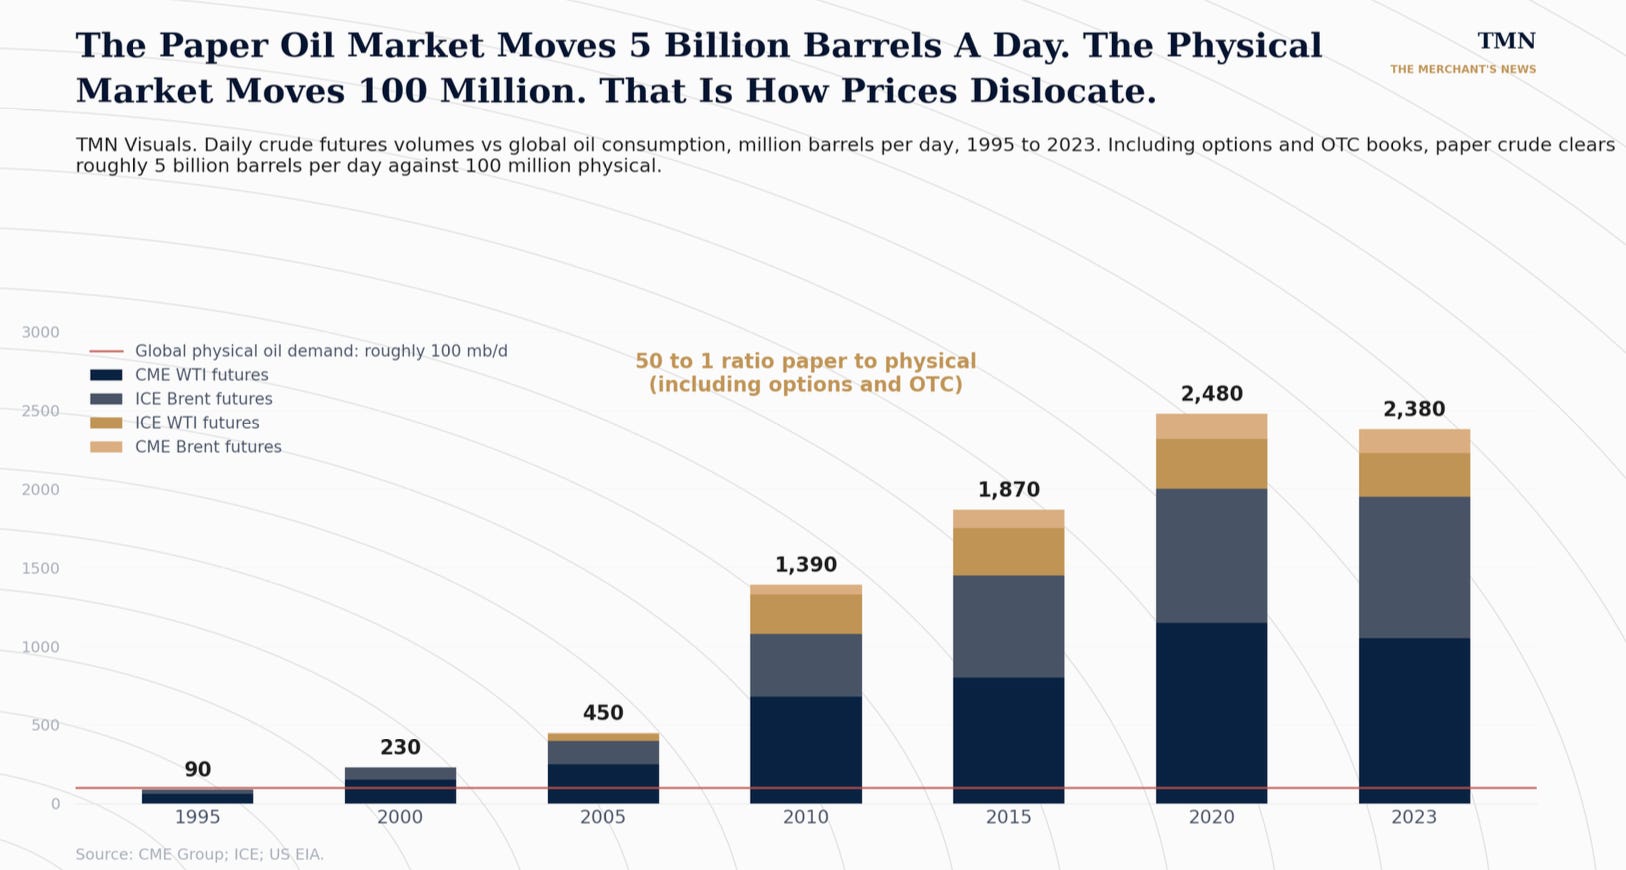
The physical oil market, the barrels that are actually produced, shipped, refined and burned, moves roughly 100 million barrels per day globally.
The paper oil market, the futures, options, swaps and OTC derivatives that traders use to bet on the price of oil, moves approximately 5 billion barrels per day.
That is a 50 to 1 ratio of paper to physical.
For every barrel of physical crude that changes hands, 50 barrels of paper crude trade on CME, ICE, and OTC books. The ratio has ballooned since 1995, when futures volumes were a small fraction of physical demand. Today the paper market dwarfs the physical market by 2 orders of magnitude.
The consequence is straightforward.
When positioning shifts on futures desks, prices move independently of physical reality for weeks at a time. That is exactly what happened between mid June and early July.
The CFTC and ICE net positioning data on Brent and WTI, shows managed money aggressively cutting long exposure into the peace deal narrative. Money managers flipped net short WTI for the first time on record.
Systematic strategies unwound war premium length ond oil fell hard in weeks, then reversed, even though the physical market was still short refined product, Russian refineries were still under attack and Chinese storage was still drawing down.
This is why I did not sell into the drop.
The physical fundamentals underneath the paper move did not break. They kept telling the same story I have been telling since June 11. Structural supply constraints on refining. Structural LNG monopoly emerging. Structural Chinese energy dependency.
Only the paper narrative changed.
Now the paper is unwinding back into physical reality.
Oil is rising this week and the paper market got ahead of itself.
The physical reasserted.
The weekend confirmed what the physical market has been saying for a month.
What The Weekend Just Showed
US Iran tensions have re-escalated.
Following the July 7 revocation of the Iranian oil license, US Central Command has carried out repeated strikes on Iranian targets since July 8.
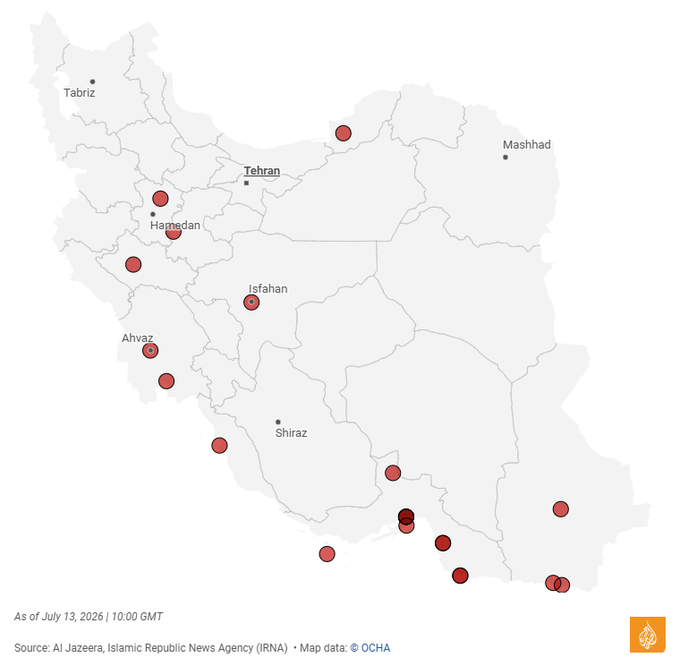
Per Al Jazeera reporting, the strikes concentrate on southern Iran and specifically on degrading Iran’s ability to continue attacks on commercial shipping. Tehran itself is deliberately not in play. This is a targeted degradation of Iranian naval capacity, not a wider air campaign.
The message from Washington is clear: freedom of navigation is not negotiable. Iran’s response, per IRNA, was that it will not be forced to pay the enemy for ship passage, which telegraphs continued asymmetric harassment of tankers.
Ukrainian drone strikes on Russian refineries continued at pace. Approximately 2 mb/d of Russian refining capacity remains offline, roughly 1 out of every 3 barrels of Russian refining.
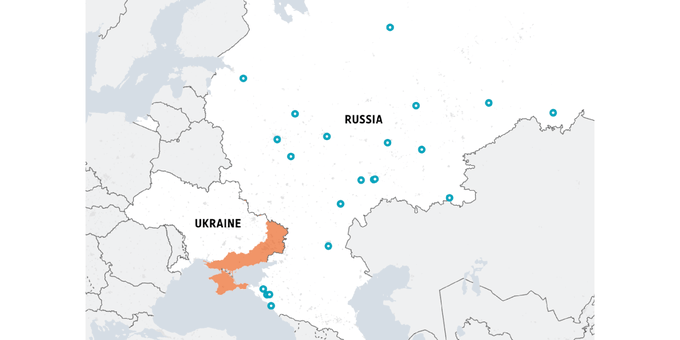
There are reports of 10 to 36 hour queues at Russian gasoline stations and fights breaking out at pumps.
This is Ukraine attacking Russia’s ability to move, not just its ability to sell.
Global refining margins are printing at levels last seen in 2022.
The US 3-2-1 crack spread is at its highest level since 2022, per EIA data.
European ICE gasoil cracks are near $50 per barrel, more than double where they were a year ago.
And ADNOC launched a new integrated global LNG marketing and trading platform in Abu Dhabi
Global Market, targeting 47 million tonnes per annum of combined marketable LNG by 2035.
That is Abu Dhabi telling the market it plans to compete directly on LNG supply.
Every 1 of these events validates the physical thesis I spent weeks stress-testing.
What This Means For My Portfolio?
So here is where I am.
The portfolio was under pressure for 3 weeks because the paper market believed the peace deal would end the resource war.
I did not believe it, but I had to test the thesis rigorously before I could trust my own conviction.
The 5 articles were the stress test, the weekend was the payoff.
The market that thought the war was over is now watching Russian citizens queue for 36 hours at gasoline pumps and US refining margins print at 2022 highs.
My portfolio was built for the physical regime, and the scorecard proves it.
12 of my 13 positions are positive.
The biggest position is up 33% since entry, driven by the American LNG monopoly thesis playing out in real time.
3 other positions are up more than 13%. The only red name is down 16%, and here is the honest piece: I had already flagged it as a watch bench a month ago, and I trimmed the position before it took the deeper drop. That trim protected the downside.
Average return across the portfolio is roughly 9%, achieved during a period when oil fell hard on paper positioning. The physical thesis did not need the paper narrative to work.
And the next thing I am working on is a picks and shovels royalty candidate under a probation window, a toll business trading at roughly 5 times trailing free cash flow with a double digit cash yield.
Below is the full position by position update: entry, current price, action taken, and what would force me to trim further.
The paid update below walks name by name: 13 positions with entry, current price, and P&L, the 3 trades I made in the last 4 weeks, and what would force me to trim any of them further.
And I share the 1 new picks and shovels name I am currently stress-testing before it enters the portfolio, with the exact business model, the numbers I am watching, and the probation window I am putting it through.
