

In case you missed it, here is the previous article:

Dear Merchants,
In March 2000, President Bill Clinton stood at Johns Hopkins SAIS and argued that admitting China to the WTO would not just open Chinese markets to American exports. It would import into China one of democracy’s most cherished values, economic freedom.
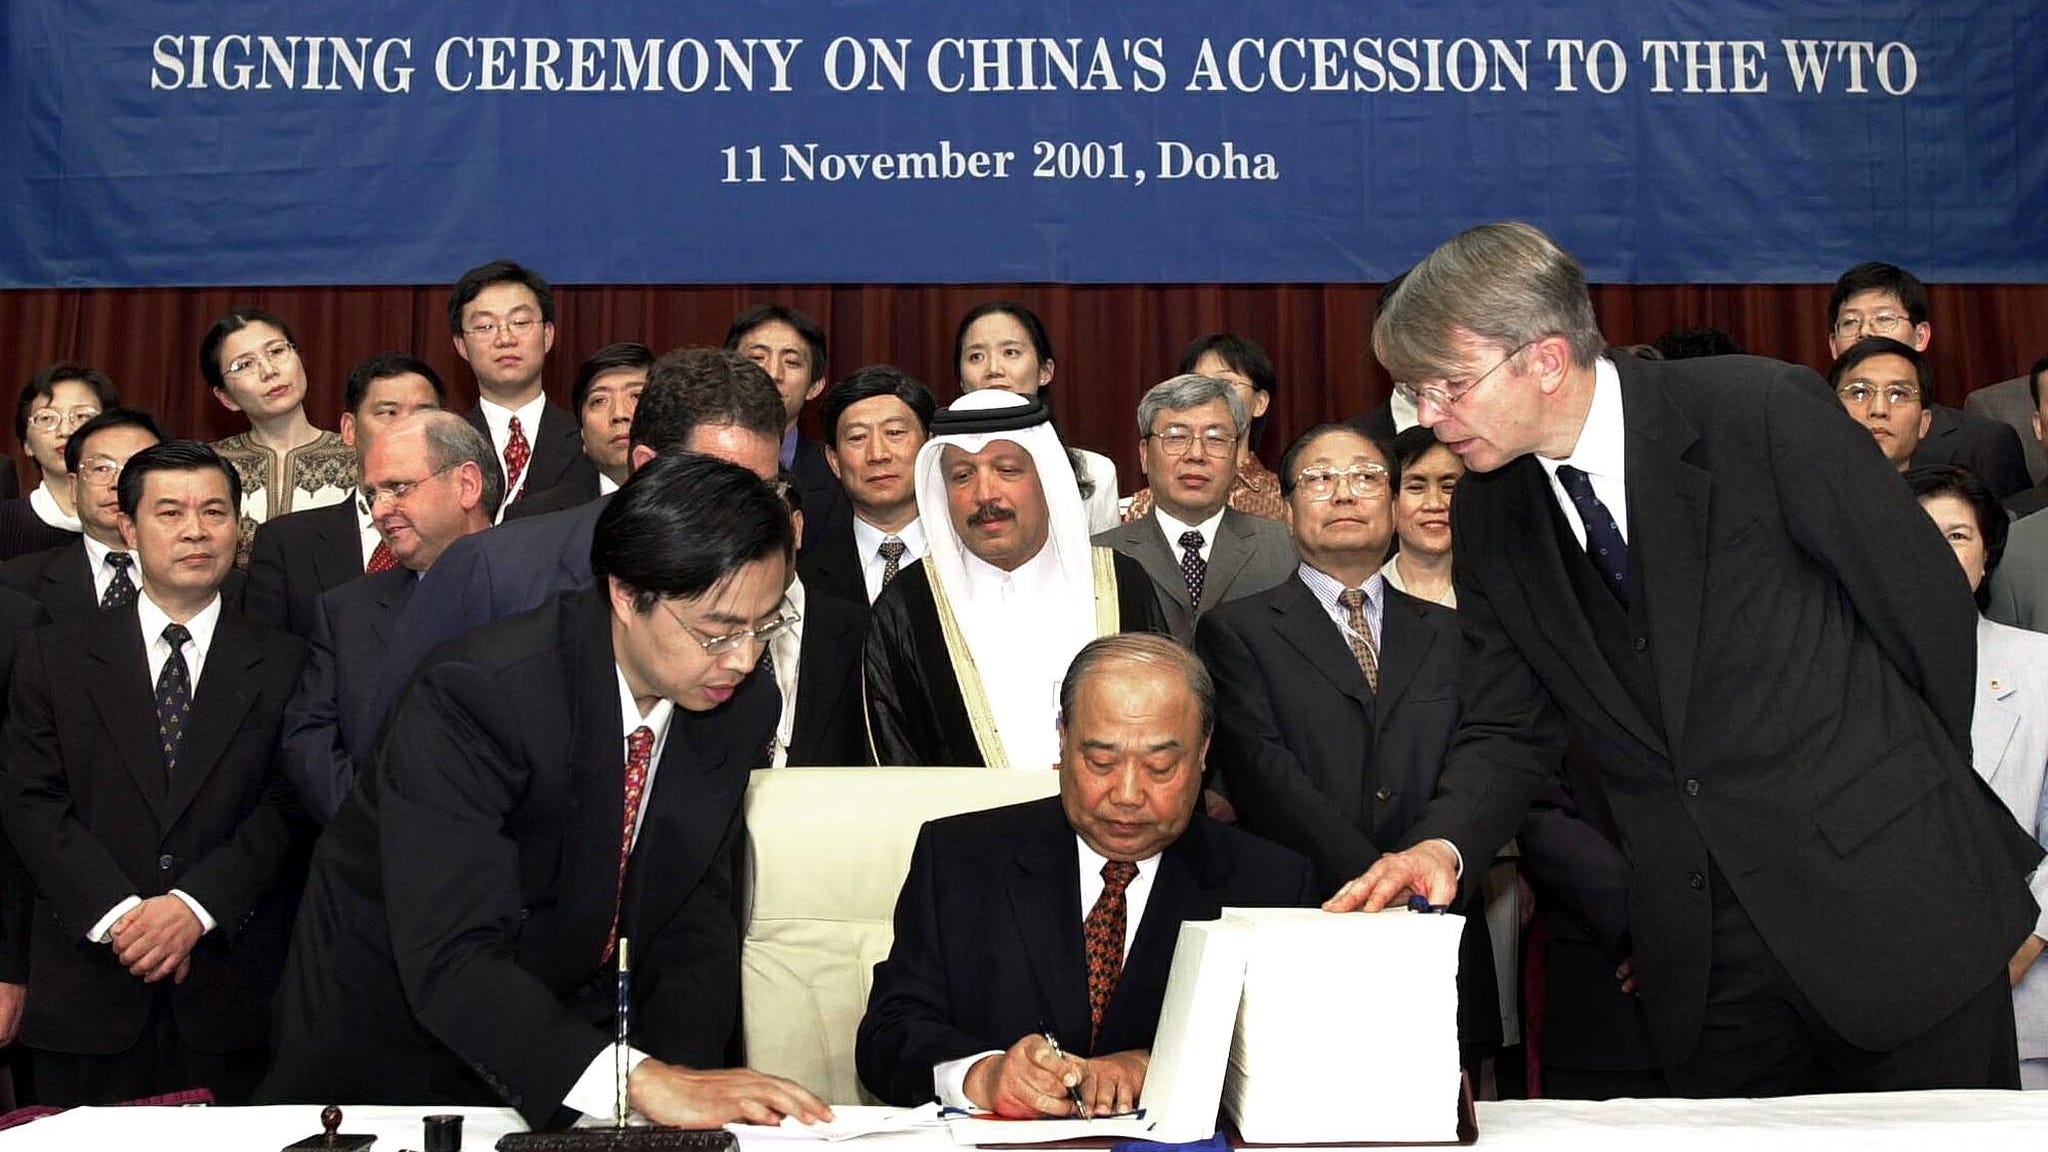
The consensus of the moment saw Chinese integration as a good deal for the United States.
25 years later, China closed 2025 with a trade surplus of approximately 1.19 trillion dollars, the first country in modern history to cross the trillion dollar threshold.
In the first months of 2026 alone, the surplus is already 451 billion dollars, on pace to exceed 1 trillion again.
Meanwhile, on 13 December 2025, German Chancellor Friedrich Merz stood at a CSU conference and declared that the decades of the Pax Americana had come to an end.
The 2000 consensus was wrong, the world order it modelled has ended.
What comes next is not free trade.
It is a resource war and the way Washington is answering it is with liquefied natural gas.
The Trillion
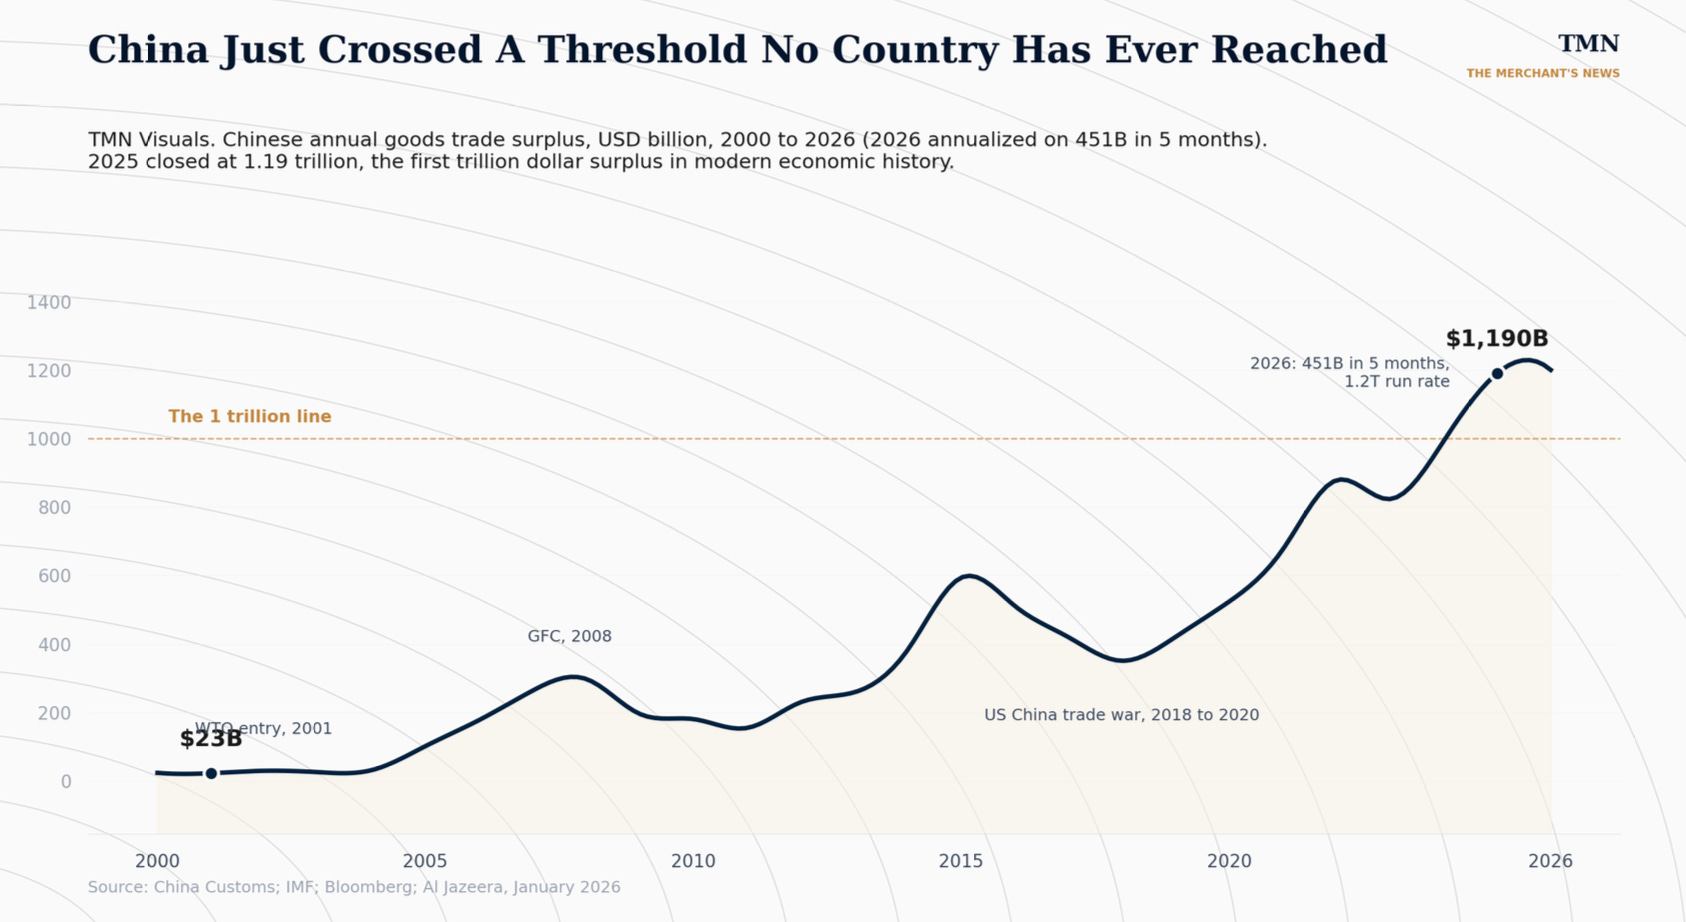
China ran a commercial surplus of approximately 1.19 trillion dollars in 2025 and the first 5 months of 2026 have already produced 451 billion dollars, per Chinese customs data, on pace to clear 1 trillion for the second year running.
The surplus is not an accident… It is doctrine.
In 2020, Xi Jinping formalized dual circulation: reduce dependence on foreign inputs, dominate global supply chains for chips, batteries and critical minerals, keep manufacturing as the permanent heart of the Chinese economy, and never abandon low cost production.
Japan, Germany and South Korea graduated out of low margin manufacturing.
China refuses.
It wants to make everything, from toys to next generation aircraft.
Look at what happened, not what was predicted, from 2001 to 2010, US imports from China rose by more than 250 billion dollars while American exports to China rose by only 70 billion.
That is a 3.5 to 1 ratio in the wrong direction.
In 1965 the American manufacturing sector employed approximately 17.1 million people. By March 2010 it was 11.5 million, most of it concentrated in the decade after Chinese entry.
Oren Cass of the American Compass think tank calls this the empirical refutation of the free trade optimism of the year 2000.
Those workers did not move into higher wage service jobs, they moved into lower quality ones, in different places, in different lives.
The auto industry is the cleanest symbol, 2 decades ago foreign automakers held 60% of Chinese car sales. Chinese electric vehicles have flipped it, and foreign share is now under 40%.
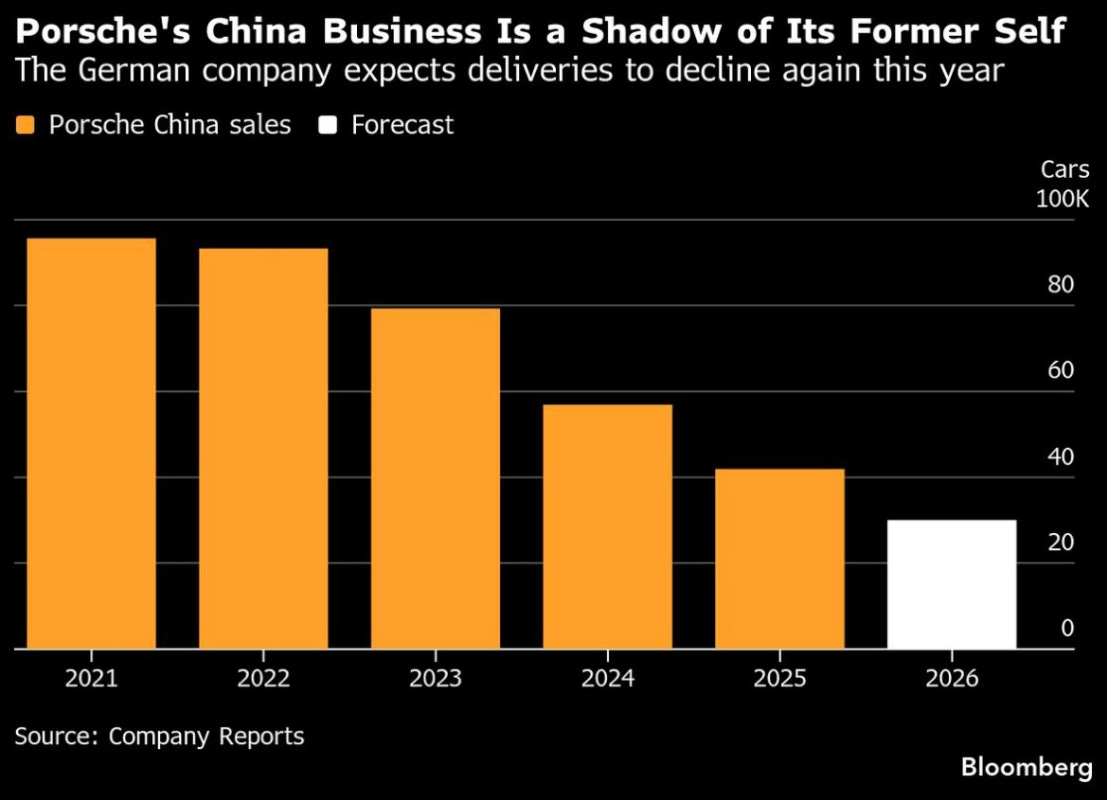
The deeper win sits upstream.
Financial Times and Bloomberg reporting has documented Chinese startups pulling ahead in humanoid robotics, because the supply chain that builds batteries and EVs already contains most of what a robot needs.
Cass has a phrase for this, what you produce today shapes what you can produce tomorrow.
Trump’s protectionism cut Chinese exports into the US, but the water found other channels: Europe, Southeast Asia, Africa, Latin America.
Deterrence moved the flow, it did not dry it up.
The imbalance is now physical, for every container that leaves Europe for China, 4 containers move in the opposite direction!
Every 1 percentage point of Chinese growth used to add roughly 0.2 points to global growth.
Goldman Sachs now calculates it will generate minus 0.1 points in the rest of the world.
Chinese prosperity now translates into industrial recession elsewhere.
Mexico answered with a 50% super tariff, Europe with investigations, Southeast Asia with antidumping actions. Xi answers back with competitive devaluation of the yuan, which makes Chinese exports even more aggressive on price.
The Weapon
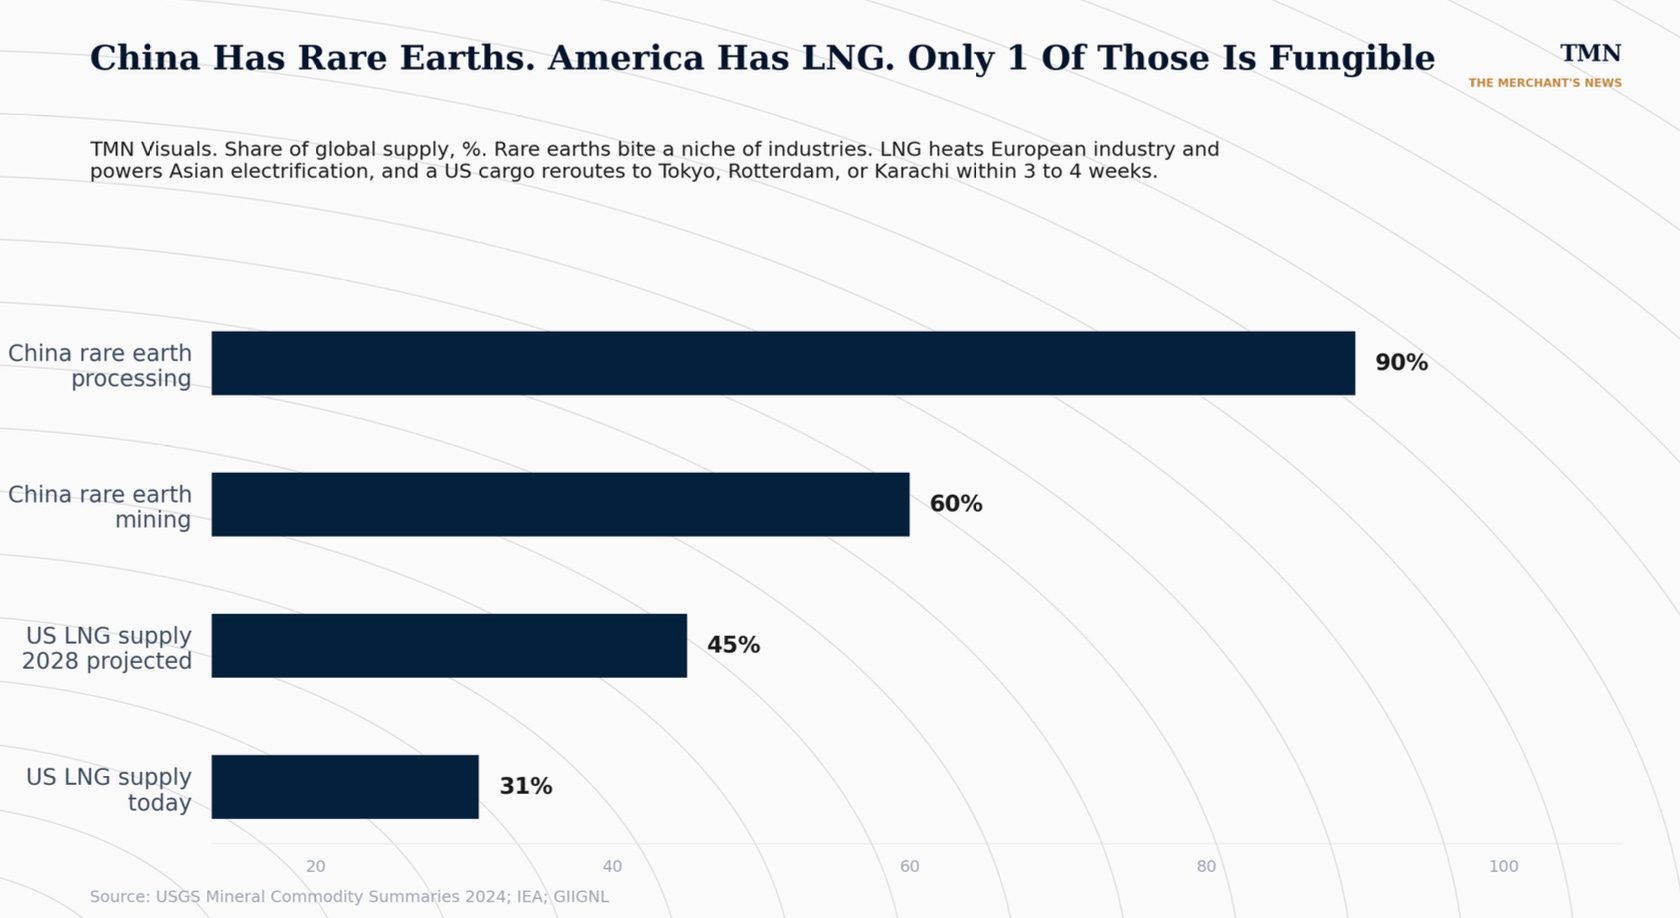
Cambridge political economist Helen Thompson argues in “Disorder” that the modern order started fracturing in 2005, not 2017.
The Iraq war split NATO. France and Germany aligned de facto with Russia. Senate pressure for a harder China trade line was already bipartisan. Oil production stagnated exactly as Chinese demand accelerated and Germany decided to build Nord Stream 1 by concluding that Ukraine was an unreliable transit partner.
That 2005 German decision is the moment the European energy order started to break.
Then 2008 widened the economic divergence between the US and Europe, and the American shale boom made the gap structural.
China’s response to the financial crisis, and America’s reaction to the 2010 Chinese rare earth embargo against Japan, traced the arc of the rivalry we live inside today.
Any situation where large scale energy importers coexist without a dominant power capable of containing them leads to terrible conflicts.
That is Europe and Japan in the first half of the 20th century.
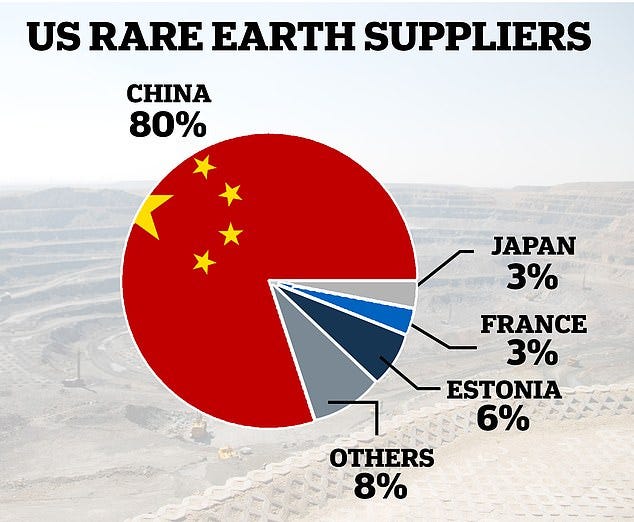
The pattern is back. What is new is that great powers with export capacity in at least 1 strategic sector now use resources as a geopolitical weapon.
(examples: the United States in natural gas, China in rare earths)
The US and China are technological rivals.
The US and Russia are energy rivals.
Each competes for influence in resource rich regions, from the Middle East to the Arctic.
China has already shown how the weapon fires.
In 2010, Beijing embargoed rare earths against Japan over the Senkaku Islands. 15 years later, when the Netherlands tried to restrict Chinese control of the chipmaker Nexperia, Beijing blocked chip exports and paralyzed European assembly lines.
The same playbook has hit lithium, Canadian agricultural products, and Japanese fish. Retaliation is no longer an emergency tool… It is ordinary Chinese trade policy.
There is a subtler lesson in the playbook.
In the 2010s, China quietly used tariffs and protectionist pressure to push Tesla into building its main production center in Shanghai. That handed China the end to end EV supply chain that today underpins its dominance in EVs, batteries, and now humanoid robotics. A commercial concession that was a strategic capture. That is the level of patience the West is up against….
The Answer ?
In a world where everyone uses energy as a strategic weapon, Trump has understood he can use it even better than the Russians and the Chinese.
American self sufficiency in oil and gas, which dates back to the Obama era, gives Washington a base that Moscow and Beijing simply do not have.
This is not improvisation.
The US National Security Strategy published on 4 December 2025 commits, in its own text, to the strongest and most technologically advanced economy in the world, the most powerful industrial base, and a “highly productive energy sector, which will be an important factor in exports.”
That is Washington declaring energy dominance a national security priority.
The same doctrine powers the Venezuela and Iran acts that we saw and the LNG buildout.
The Japan Institute of Geoeconomics read of that document says it plainly. From Tokyo, Trump and Vance invented nothing. The equation national security equals economic security has been the operating logic of every major East Asian government since 1945.
Europe is the outlier.
Which is why, on 13 December 2025, Friedrich Merz told a CSU conference that “the decades of the Pax Americana have come to an end” and that Europe must now defend its own interests.
A sitting German Chancellor, in public, declaring the post 1945 security architecture finished.
Now put the LNG map next to that speech.
The United States is the world’s largest LNG exporter. The 2nd largest is Qatar, and in March 2026 Iranian missile strikes on Ras Laffan took approximately 12.8 mtpa offline, about 17% of Qatari export capacity, on a 3 to 5 year repair timeline. On 6 July 2026 the Nakilat tanker Al Rekayyat was struck near Oman, equal no de escalation. The 2nd largest supplier is structurally impaired.
The largest is expanding capacity every quarter. If China uses rare earths as a weapon, America has a sharper one in LNG and unlike rare earths, LNG is not a niche input. It heats European industry in winter and will fuel Asian electricity demand for the next 15 years.
This is the mechanism Washington is already deploying.
So the resource war has entered a new phase, with China’s trillion on one side and America trying to reach LNG monopoly on the other.
Behind the paywall, I walk through China’s hidden vulnerability, why American LNG is the sharpest weapon in the trade war right now, and what my portfolio is doing about it.
China’s Hidden Weakness:
