

Dear Merchants,
Last year, everyone in oil was telling the same story… a flood of new supply was coming, demand was stalling, and the 2026–2027 market was going to drown in barrels.
The IEA’s 2025–2026 outlook looked brutal on paper.
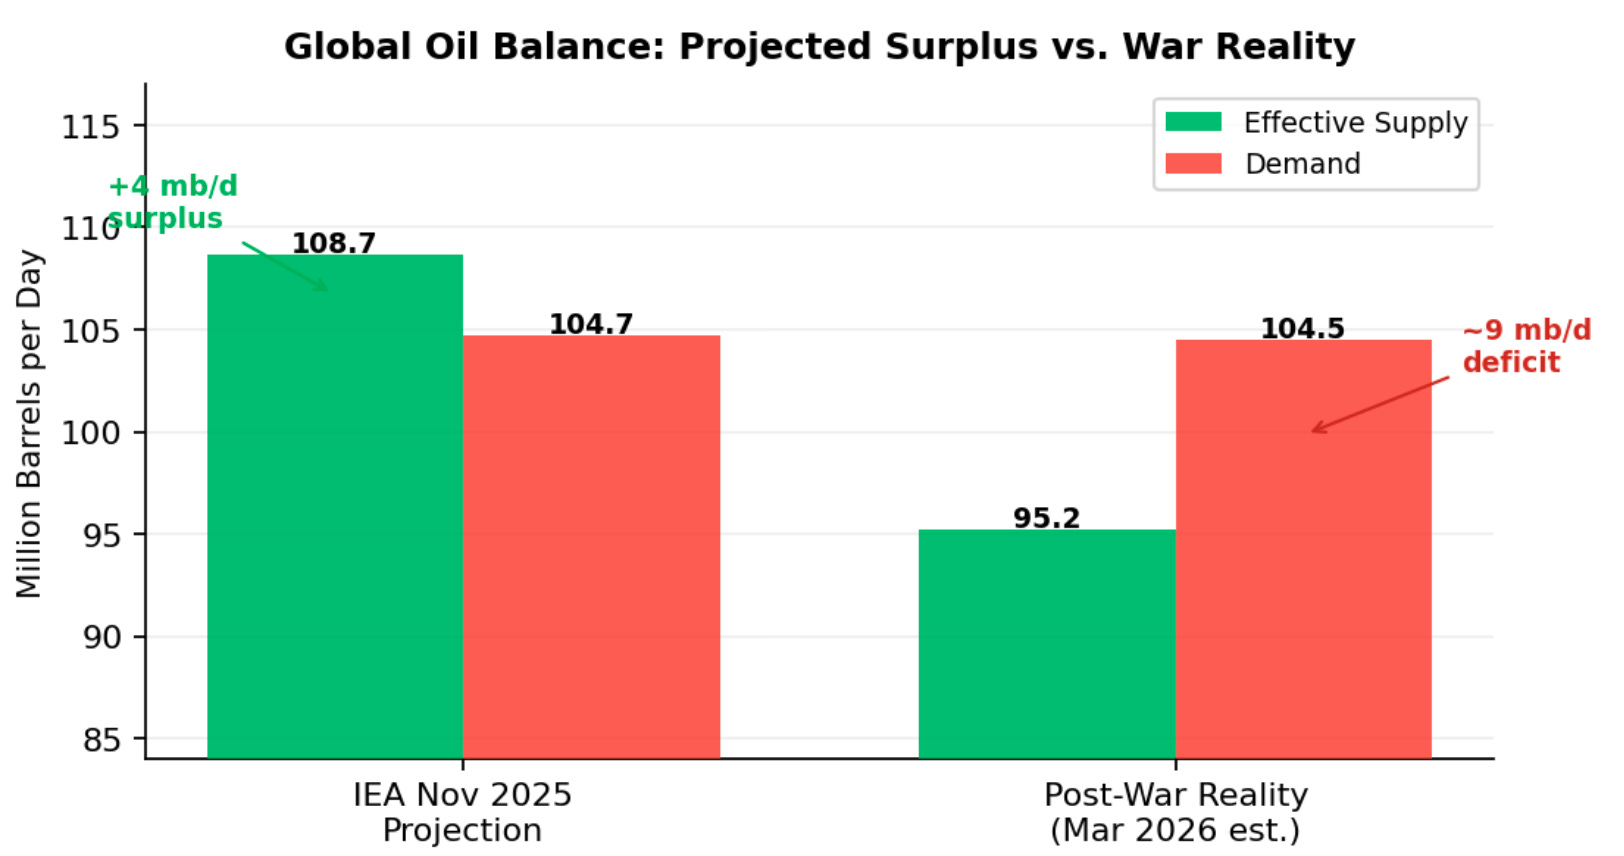
In its November oil market report, the agency projected global supply rising to roughly 108.7 million barrels per day by 2026 as OPEC+ lifted its cuts and new production from the US, Brazil, and Guyana came online.
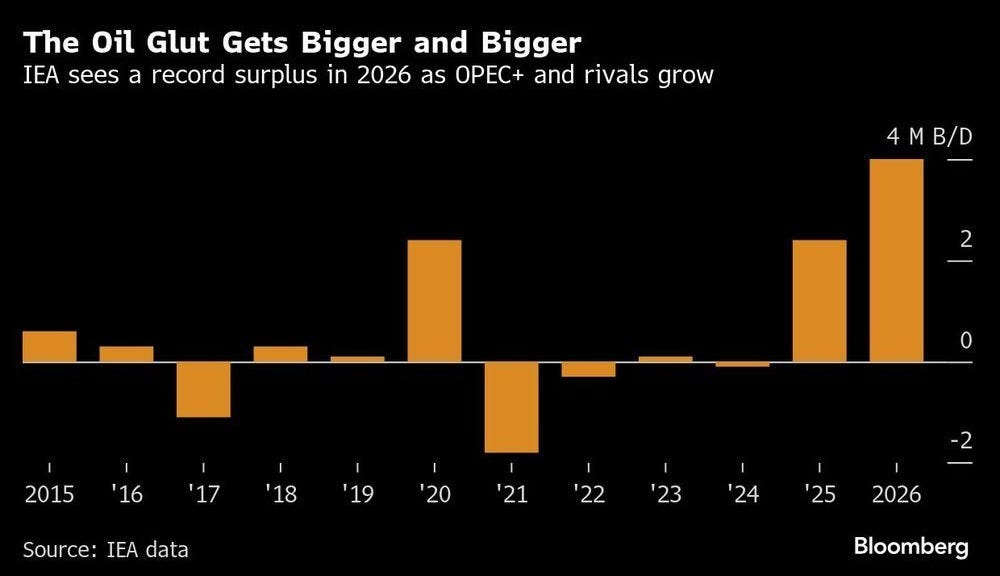
Demand was expected to grow by only about 770,000 barrels per day, leaving a potential surplus of around 4 million barrels a day nearly 4% of global consumption. That’s the “oil glut” headline everyone grabbed onto.
Prices played along with that story. Brent slipped into the low 60s, WTI into the high 50s, and for 3 straight years Brent closed the year lower than it started something that had literally never happened before in that sequence.
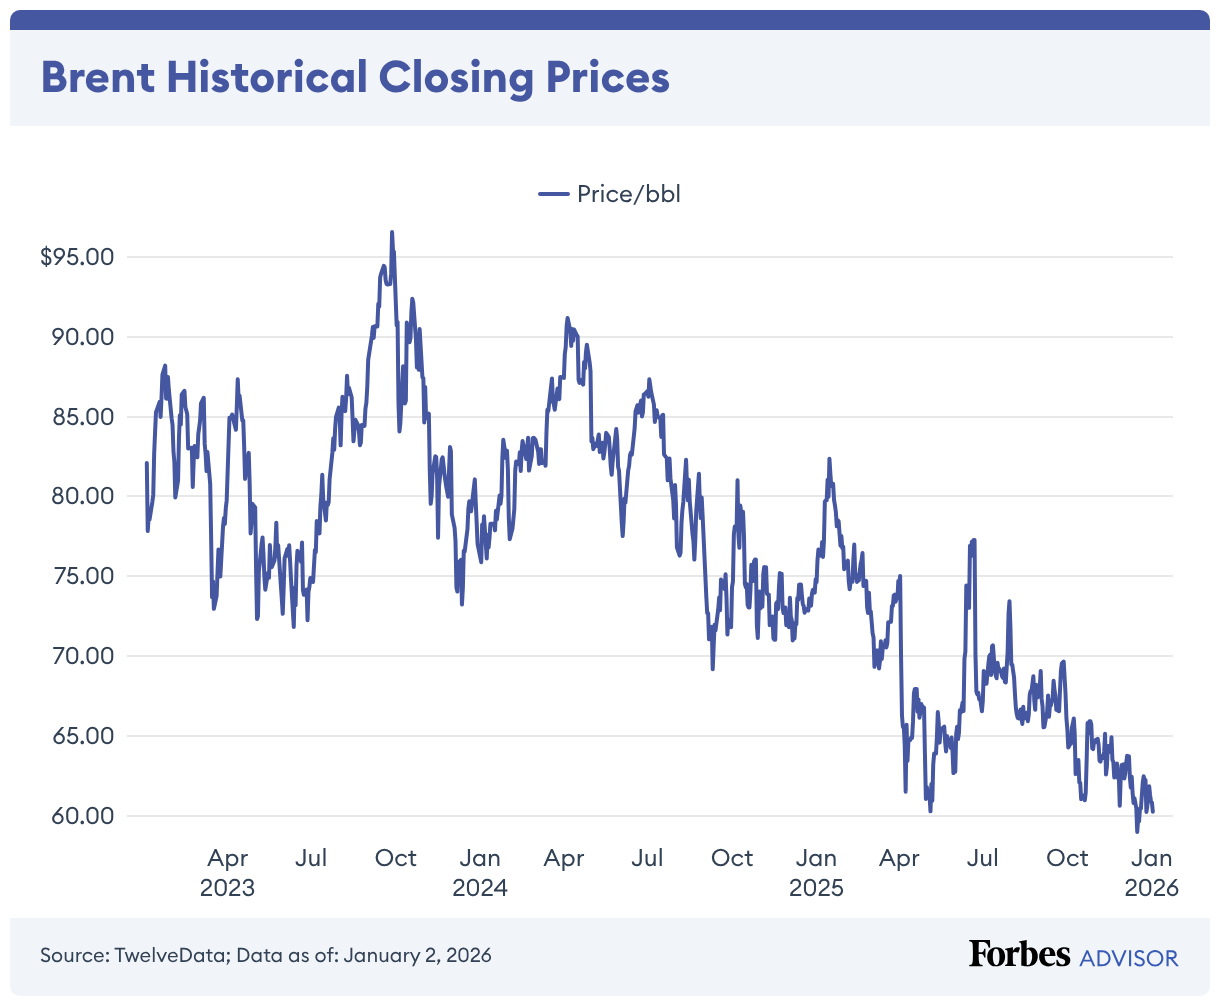
The market was spooked every geopolitical flare up got sold into, every rally became an exit opportunity, and commentators declared oil “boring and range bound” around 60–65.
But even then, the foundations of the glut story were wrong.
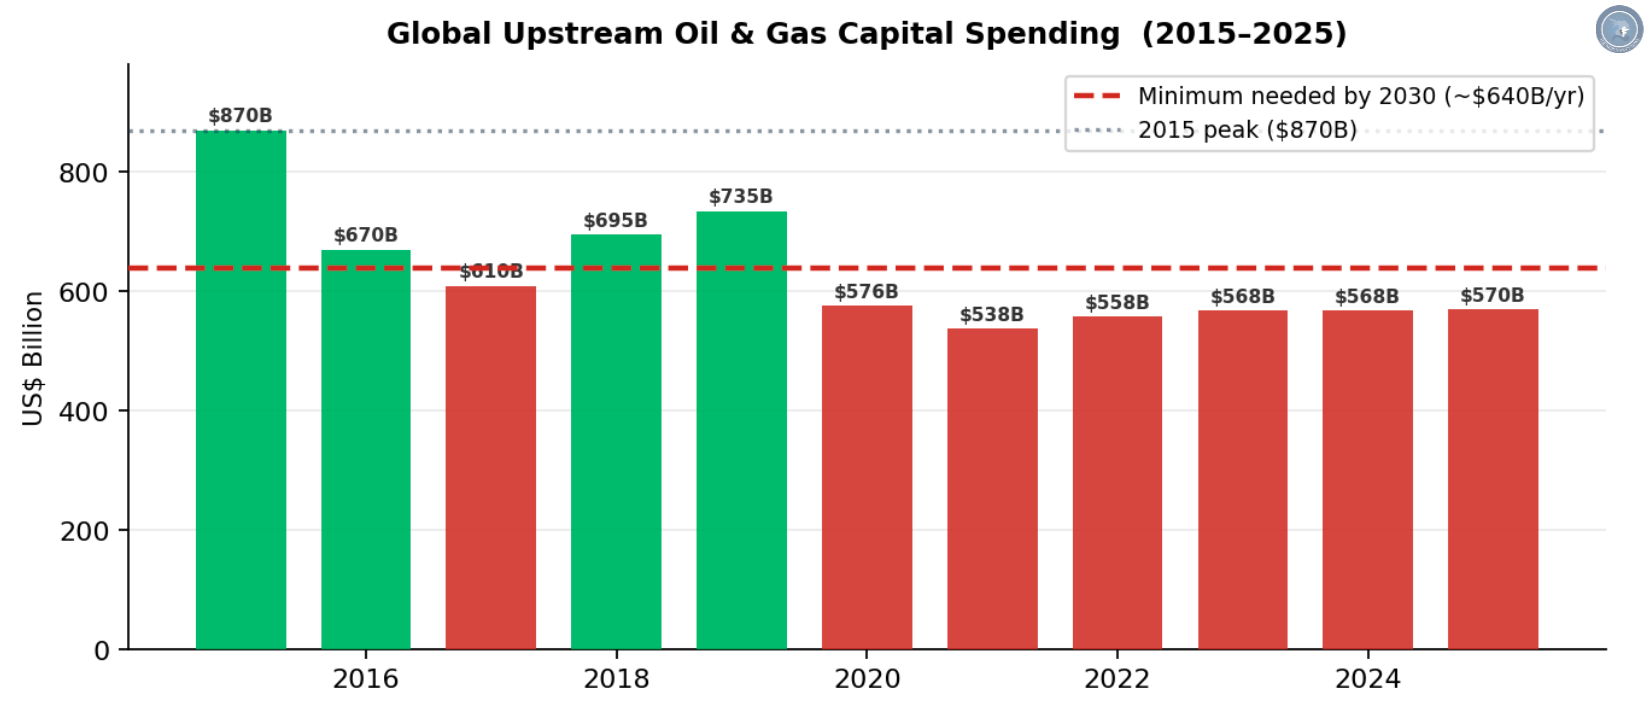
Underneath the IEA spreadsheets, the industry had been underinvesting for years. Global upstream oil and gas spending in 2022–2023 sat around $500–570 billion per year, still 35% below the mid 2010s peak even though costs were higher and so was demand.
The International Energy Forum estimated the world would need roughly $640–738 billion per year of upstream spending by 2030 to avoid a supply crunch, which adds up to a trillion dollar hole over the decade if nothing changed. On top of that, the IEA itself was warning that existing fields lose roughly 6% of their output every year, and that without continuous investment, those declining fields could cost the world roughly 5.5 million barrels a day every year.
In other words the “glut” only worked if everything went perfectly demand stayed weak, OPEC+ held together, geopolitics stayed quiet, and money somehow kept flowing to maintain production at these prices.
That was always a fantasy.
My argument then and now was simple:
2026–2027 was going to be a reset, not the final picture.
A period of apparent oversupply and weak prices was just the setup for the next shortage, because low prices kill the very investment needed to sustain the projected surplus.
The real danger wasn’t a “permanent glut” It was a sharp swing from a false sense of abundance to a genuine supply crunch the moment something broke.
But something just broke…
War arrives
On 28 February, the US/Israel–Iran conflict went from a shadow war to an open one. By early March, Iran had effectively shut the Strait of Hormuz to normal commercial traffic, turning the single most important oil corridor in the world into a war zone.
In normal times, about a 1/5 of the world’s seaborne oil and a similar share of global LNG passes through Hormuz.
Those flows have collapsed by more than 80% as tankers anchor outside the danger zone or reroute. The IEA calls it “the most severe oil supply disruption ever.”
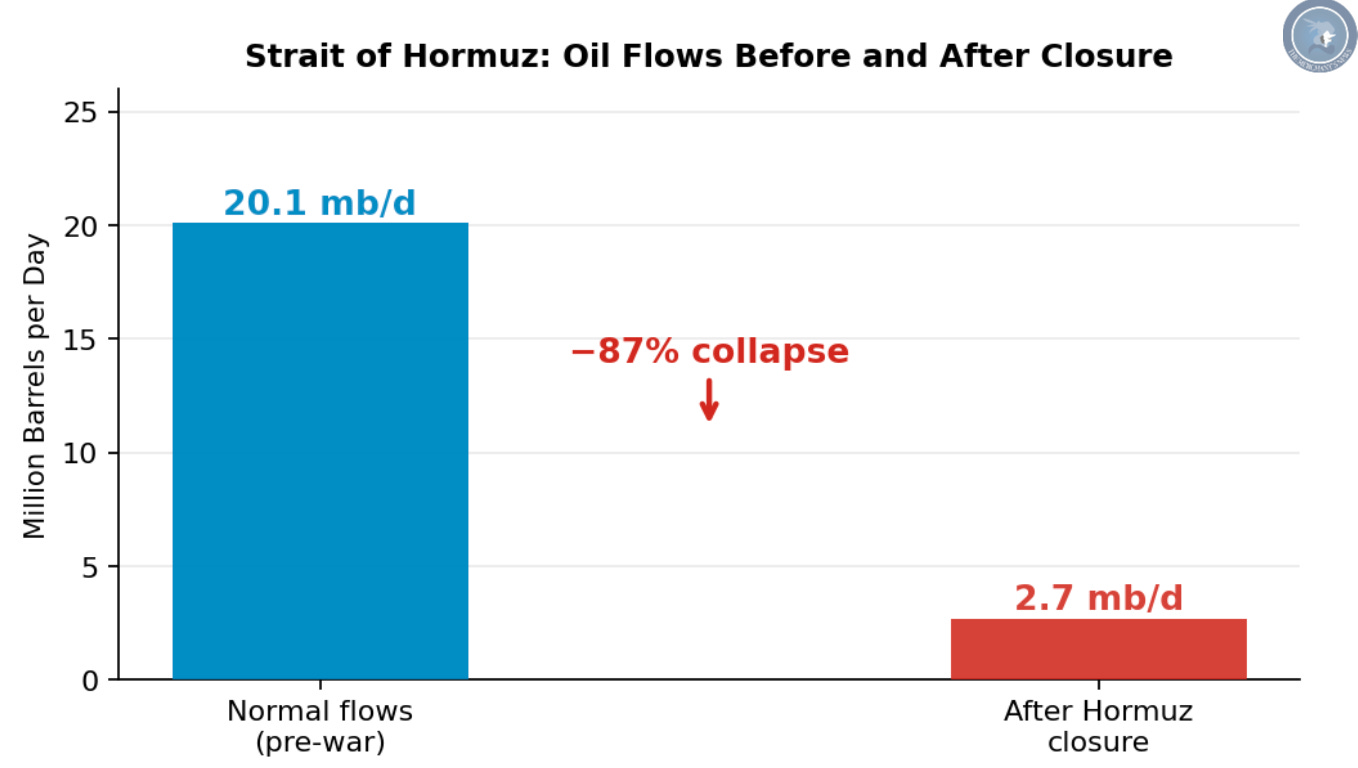
With crude exports through Hormuz falling from about 20.1 million barrels per day to 2.7 million barrels per day in just over 2 weeks. In response, the G7 authorised a record 400 million barrel release from emergency reserves, which sounds enormous until you remember the daily shortfall is somewhere around 10–15 million barrels once you subtract Iranian cargoes that are still moving to China.
Emergency reserves buy you a few weeks…They don’t create new oil.
At a 2–4 million barrel per day draw rate, 400 million barrels covers low double digit weeks of shortfall not a multi year problem.
This is the exact environment the glut theorists said couldn’t happenstocks falling, spare capacity blocked not by policy alone but by mined shipping lanes and bombed infrastructure, and a big risk premium built into every barrel that still gets through.
Infrastructure damage
The other hidden assumption in the glut narrative was that supply is “breathtakingly elastic” that whenever prices rise, US shale, Brazilian pre salt, and OPEC+ can just flood the market.
That story dies the minute missiles start landing on critical infrastructure.
🇸🇦 Saudi Arabia: Ras Tanura is a warning shot
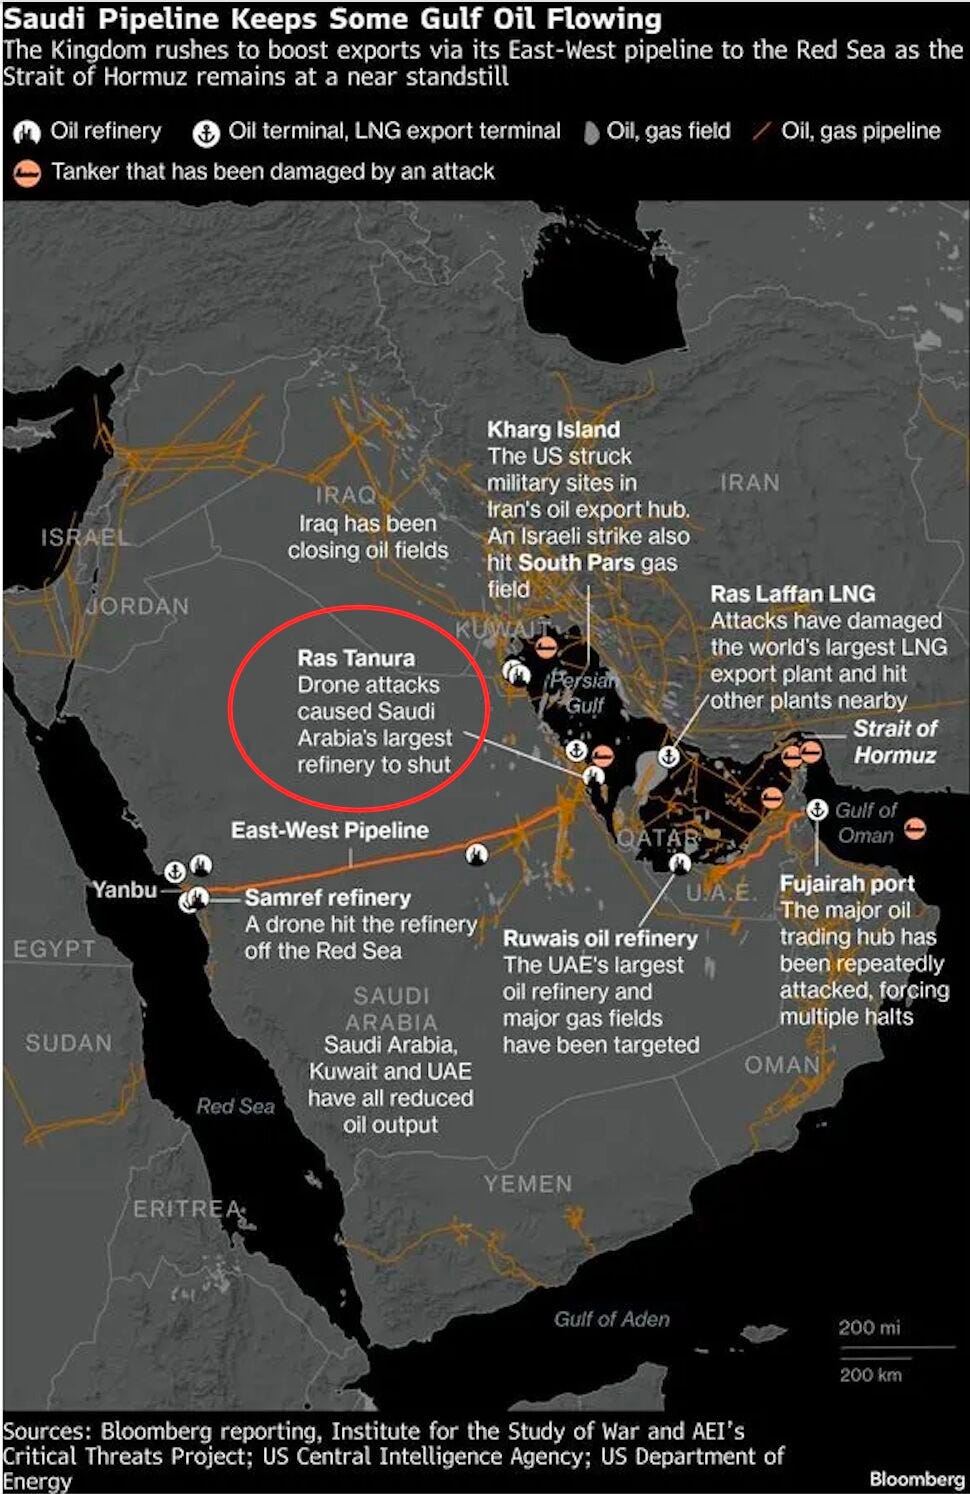
Saudi Aramco’s 550,000 bpd Ras Tanura refinery the kingdom’s largest and a key export hub was shut down on 2 March after an Iranian drone attack, then restarted around 13 March after inspections and repairs.
Officially, Saudi authorities called the incident a “limited” fire caused by debris from intercepted drones, with no sustained impact on exports.
But the signal matters more than the headline:
Ras Tanura sits at the heart of Saudi crude and product export logistics.
It has now been proven vulnerable in wartime, in a Gulf already riddled with mines and drone swarms.
Even a cautious 550,000 bpd shutdown during a period when Hormuz is already disrupted squeezes the system far harder than any of the old surplus models assumed.
In 2019, it took months to get Abqaiq and Khurais back to full comfort after a major attack in peacetime, with no restrictions on repair logistics. Today, with active conflict and elevated security risks, any serious hit will take longer to recover from, not shorter.
🇮🇷 Iran: refineries, storage, and export ceilings
For Iran itself, the war is attacking the infrastructure that turns reserves into usable barrels. Israeli and US strikes have hit multiple oil storage depots and the Tehran refinery, sparking large fires at the Aghdasieh warehouse, the Shahran depot, a Karaj facility, and refinery units around the capital.
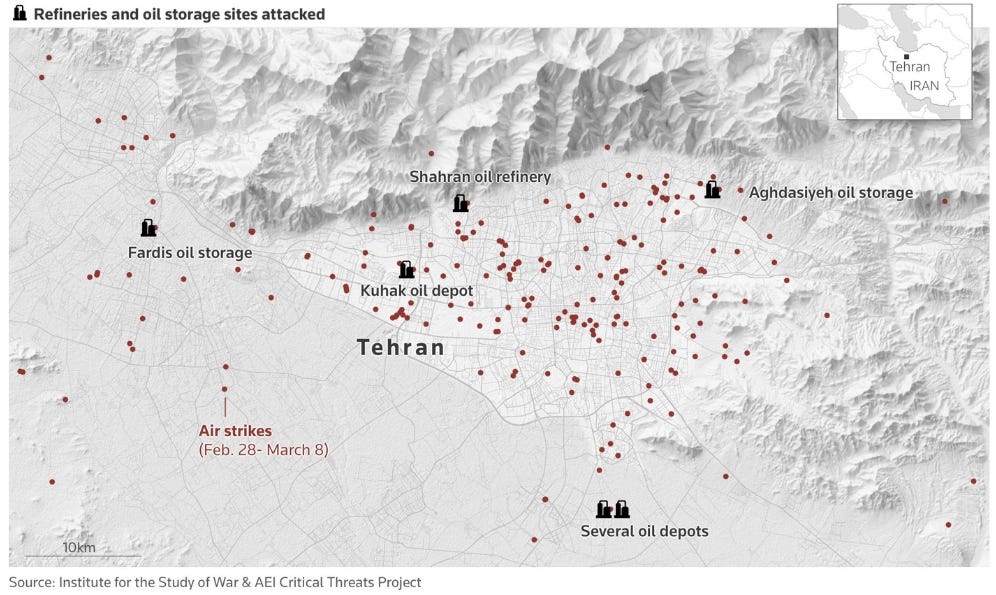
Iranian state media insist domestic fuel distribution continues, but the loss of above ground storage and damage to refining capacity reduces flexibility and slows any future export recovery even if sanctions were eventually relaxed.
Despite the conflict, Iran has managed to ship at least 11–12 million barrels of crude through to China since hostilities began, using unofficial tanker networks and alternative routes like the Goreh–Jask pipeline to get around the main chokepoint.
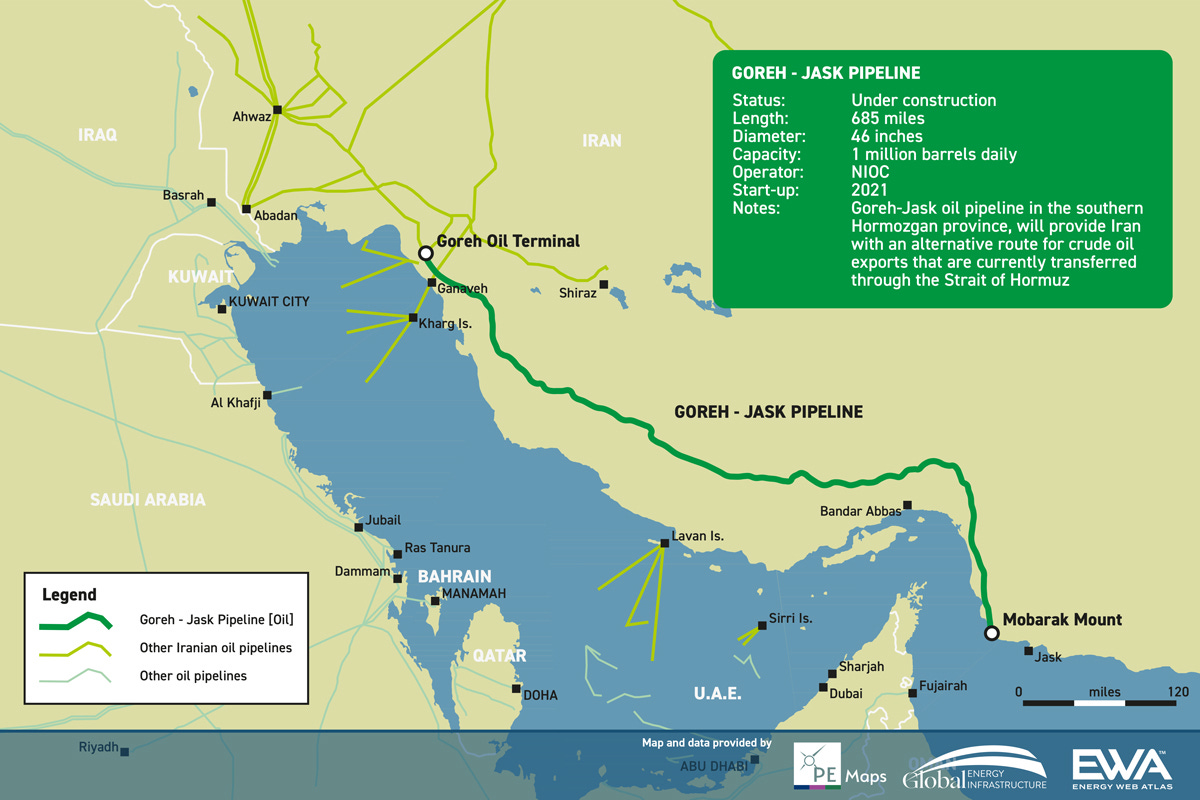
But volumes are way down from where they were before the war, fewer windows to load exist, and every cargo comes with serious political and insurance risk attached. Tehran can manage this for now. Getting back to 2–3 million barrels a day of clean, insurable exports isn’t happening any time soon.
When you add it all up:
Capacity that looked available on paper is either sitting idle because of the war or physically broken.
The key oil hubs Ras Tanura and Kharg Island for crude and products are now confirmed targets. Not theoretical ones.
Even if a ceasefire is signed, physical reconstruction and de-mining timelines run well beyond 2026.
You can only call supply “flexible” when the pipes, ports, and refineries are in one piece and someone is willing to insure them.
That’s gone now.
Underinvestment meets war
War didn’t arrive in a isolated way, it landed on top of a system that had already been spending too little on the boring parts of oil and gas for a decade.
Between 2015 and 2020, upstream oil and gas spending fell by roughly a 1/3 from around under $600 billion as ESG pressure, oil price crashes, and balance sheet discipline all hit at once.

By 2025, annual upstream investment had climbed back to the $565 billion range, but it was still well below both the old peak and what the industry needs to meet projected demand.
The International Energy Forum estimates the world needs about $640 billion per year of upstream spending by 2030 just to avoid a supply crunch a gap of about $100 billion a year compared to where spending actually sits.
The IEA’s own work on decline rates shows that without continuous investment, global production would fall by roughly 5.5 million barrels per day each year the equivalent of losing a Brazil + Norway every 12 months.
Refinery investment has been flat or falling, with global refinery spending around $37 billion and trending lower before the current conflict destroyed physical assets.
In other words, before a missile hit anything, we were already heading toward:
Non OPEC supply growth slowing in the late 2020s.
OPEC+ spare capacity shrinking as production cuts are gradually lifted.
Any demand that comes in higher than expected ,or supply that comes in lower pushing prices up just to keep things in balance.

The Iran war didn’t create a tight market. It just brought forward a crunch that was already in the making.
Add the war specific damage:
A near halt in westbound Hormuz flows.
Documented damage to Iranian refining and storage.
A whole new price tag on every Gulf infrastructure asset, including Saudi capacity that everyone called “untouchable” 3 years ago.
The result is a new reality where the world can effectively produce less, has less room for error, and every barrel carries a built in war surcharge.
Markets are starting to connect the dots, but most economists and strategists haven’t caught up yet, let’s discover it…
