

“Only when the tide goes out do you discover who’s been swimming naked.”
WARREN BUFFETT
Merchants,
Brent jumped more than 7% yesterday, closing near $100.7 a barrel. Over the past month it has ripped roughly 35%.
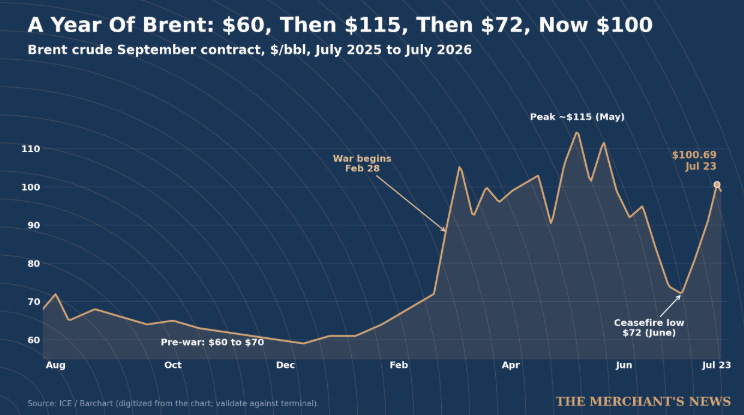
The physical market is confirming it: the front of the Brent curve has flipped from contango into backwardation, the prompt barrel now trading at a premium to later months, and one desk described the timespreads as “panic across the board.
(Backwardation is the market’s way of saying the shortage is now, not a fear of one later)
Here is why this time is different, and it has little to do with the size of the escalation.
For moths since the start of the conflict, reserve releases and quiet sanctions waivers held the water artificially high and hid how tight the physical market really was.
This week the tide went out…. In every previous spike since the US and Iran started fighting, something appeared on cue to push the price back down: a reserve release, a quiet sanctions waiver, a spare OPEC barrel.
Now none of it is available at once.
That absence is the story, and it is why the producers sitting on oil in safe, export-connected ground are the ones who win (in this article I will review one of them).
The Week Oil Stopped Pretending
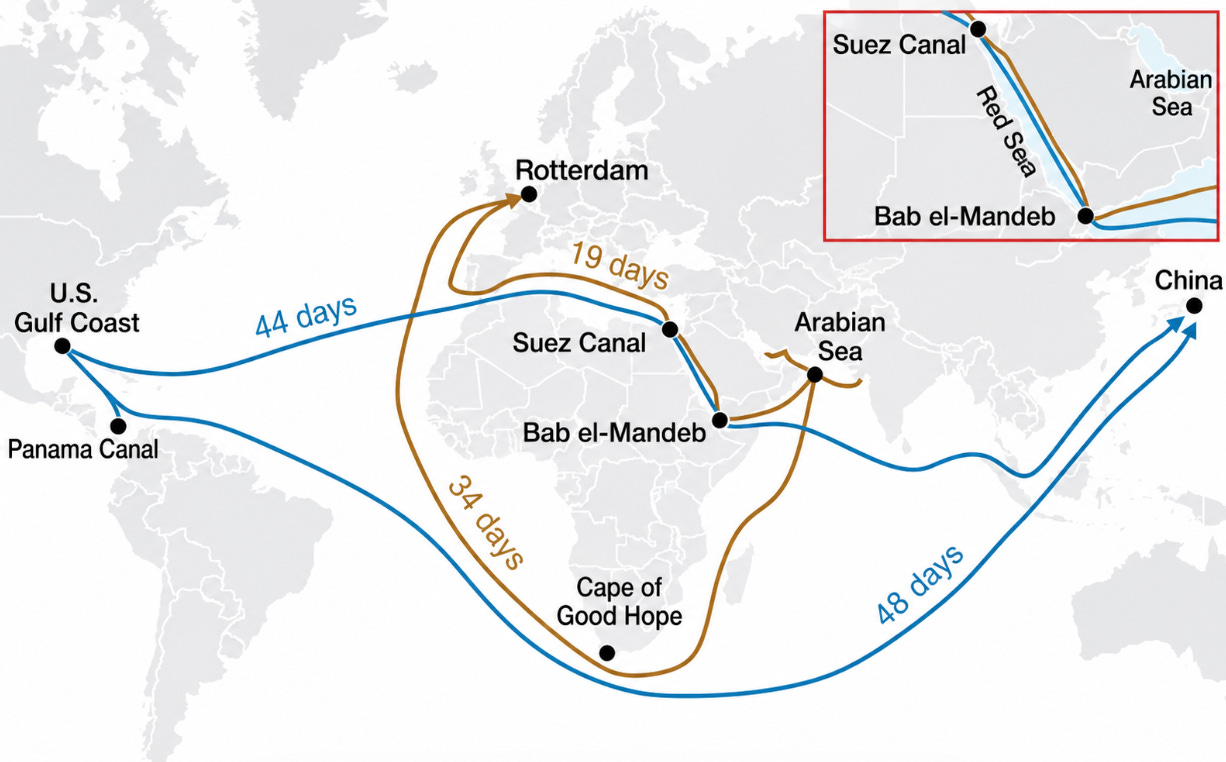
Only 30 verified vessels crossed the Strait of Hormuz between July 17 and 19, against 125 to 140 a day before the war, and diplomatic talks have stalled.
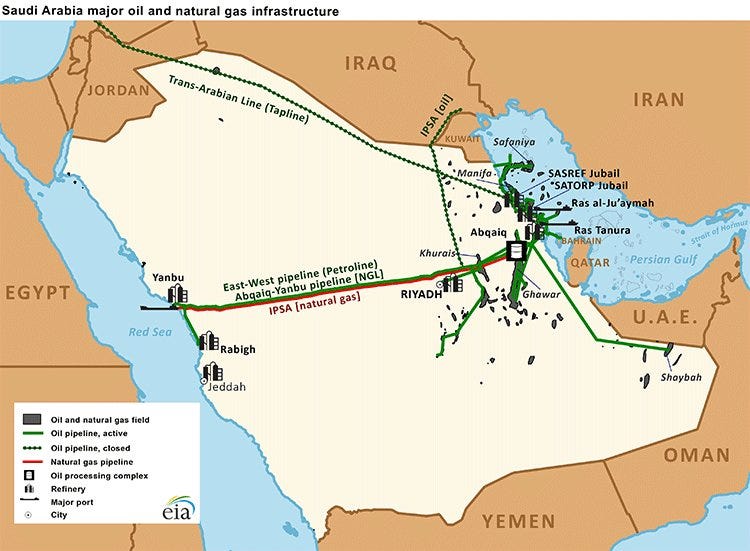
The Houthis declared a maritime embargo on Saudi Arabia’s Bab el-Mandeb route, the roughly 4.5 million barrels a day and about 75% of the Kingdom’s exports that the Yanbu terminal was built specifically to move around Hormuz risk.
President Trump told Axios he is “close” to a decision on a “massive attack” on Iran, bigger than the earlier strikes.
Almost nobody is counting the third front.
In the Black Sea, Ukraine has now landed 183 strikes on Russian vessels, 119 in the Sea of Azov and 64 in the Black Sea, on a route that moves 3.7 million barrels a day including CPC Blend.
3 maritime valves carry nearly half the world’s seaborne oil, Hormuz alone around 20%+ of it, and all 3 are contested at the same time.
And There Is No Spare Barrel On The Other Side
Contested routes would be survivable if the world held a supply cushion.
OPEC spare crude capacity narrowing to about 2.4 mb/d by 2026, down from 6.5 mb/d in 2020.
Worse, one of the few genuine holders of spare capacity, the UAE, formally left OPEC and OPEC+ on May 1 after 59 years, taking itself outside the quota and enforcement system entirely.
That leaves the United States as the swing supplier, and it has already shown its ceiling.
When Gulf routes were a war zone earlier this year and America was the only reliable barrel, US crude and product exports spiked to a record near 14 million barrels a day, about as much as its pipelines, docks and tankers can physically move.
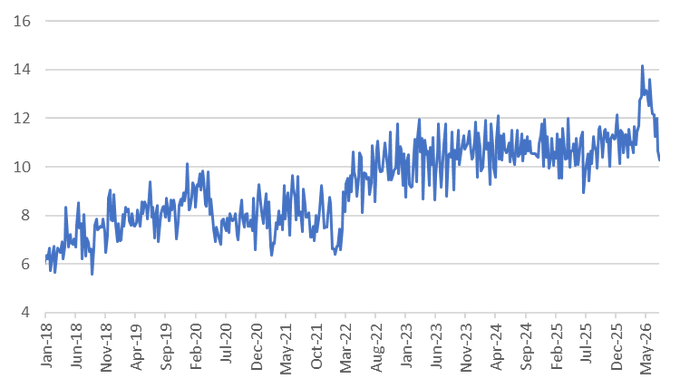
When the June ceasefire briefly reopened the Gulf, buyers rushed straight back to Saudi and Emirati cargoes and US exports eased.
Now the routes are breaking again and that demand is swinging back to the US, into a machine that already proved 14 million is close to the top.
The swing producer is not a spare-capacity producer.
It is already running flat out, and even flat out it could not cap the price last time.
The Round Trip: From Peace Deal To $100
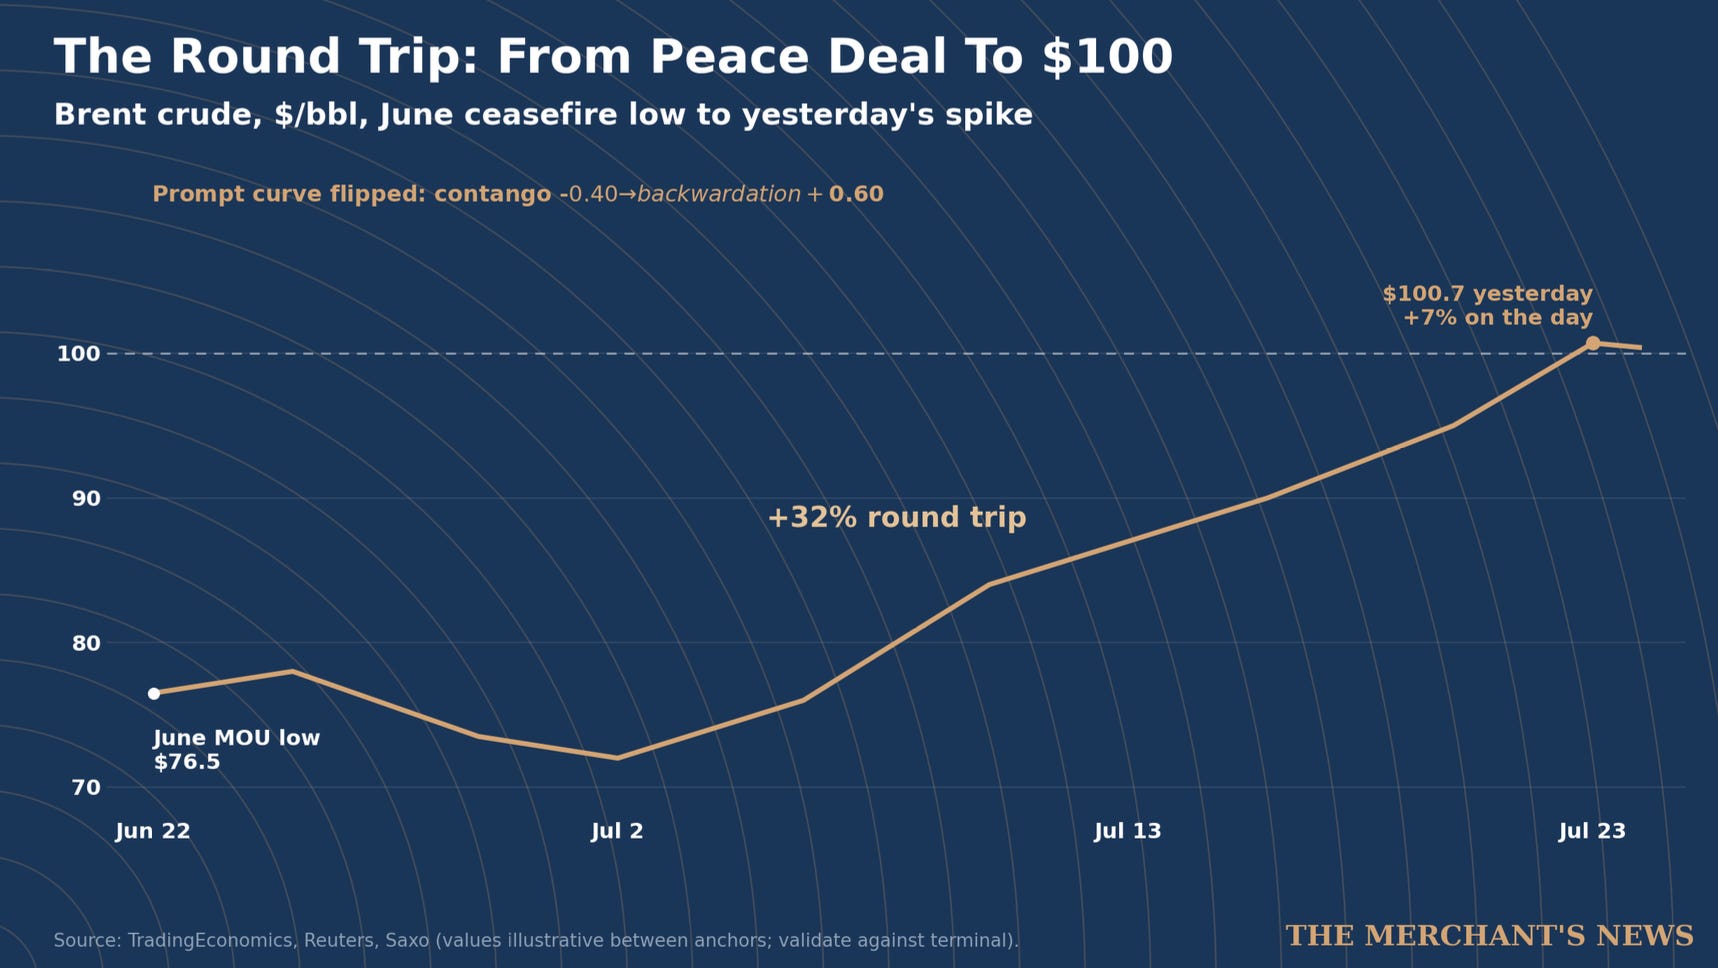
Six weeks ago this looked settled. The June ceasefire and the memorandum around it dropped Brent to about $76.5 on June 22, and by early July, as Hormuz shipments briefly normalised, the curve slipped into mild contango and the six-month spread even blew out to a discount.
Peace deal complacency was fully priced.
Then the ceasefire frayed, the attacks resumed, and the risk premium marched straight back into the front of the curve.
That is a $24 round trip, about +32%, from ceasefire optimism to war-risk pricing, with the prompt spread swinging from roughly 40 cents of contango to about 60 cents of backwardation, WTI has followed into the low $90s.
How They Used To Keep Oil Down?
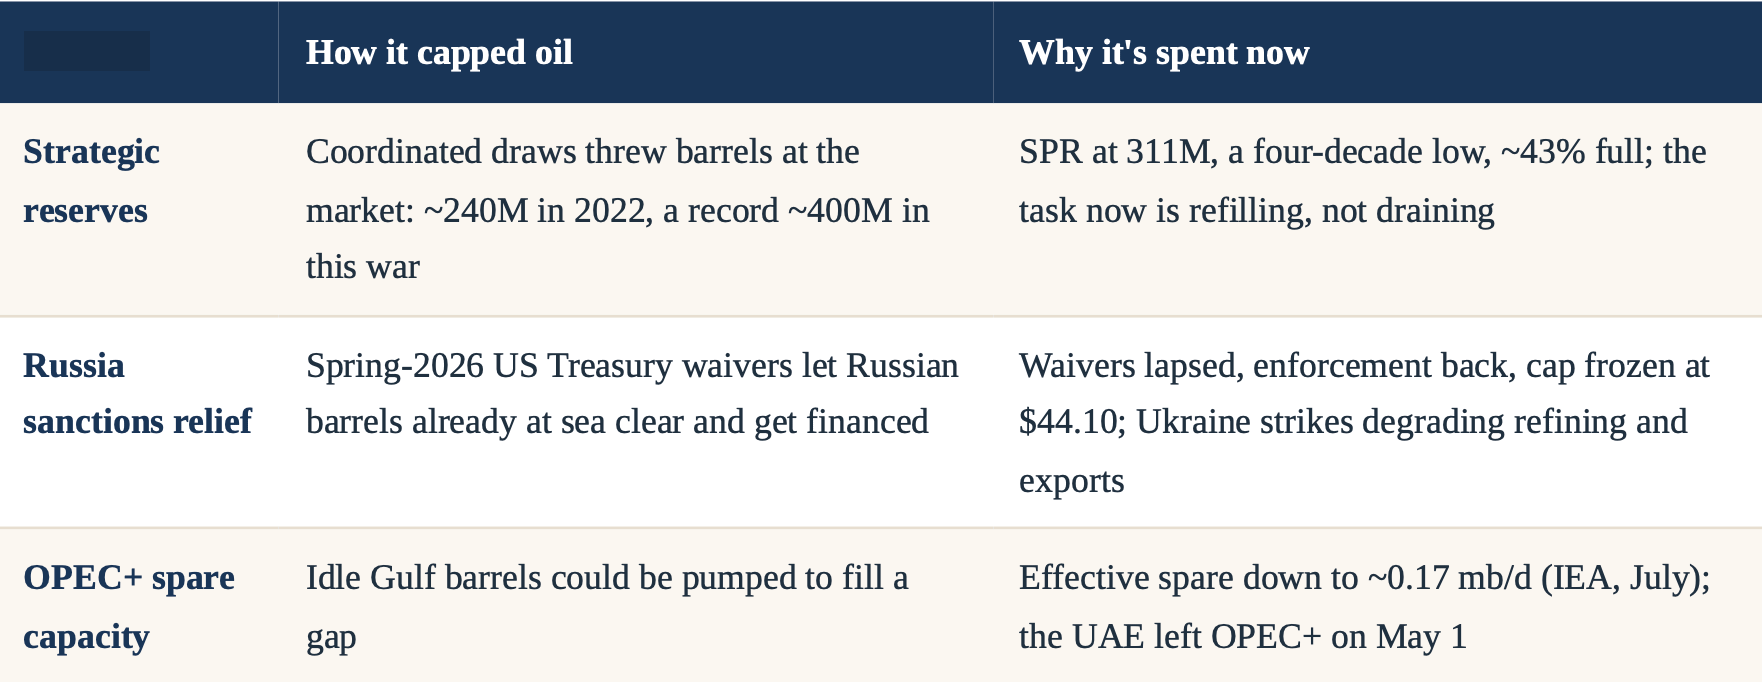
With no spare barrel and no safe route, the only levers left were the two the West kept in reserve.
The first was the strategic reserve: the US and allies would drain hundreds of millions of barrels to fake supply.
The second was quieter…
Washington softened enforcement on Russian crude, letting sanctioned barrels keep flowing so the world stayed supplied even as it condemned the seller.
Those two tools capped every spike of this war.
This week, for the first time, both are out of reach.
Why that is true, and who profits from it, is the rest of this note.
It is important to highlight, as I did in my previous article, China’s role in the oil price story.
China is slowing its crude imports.
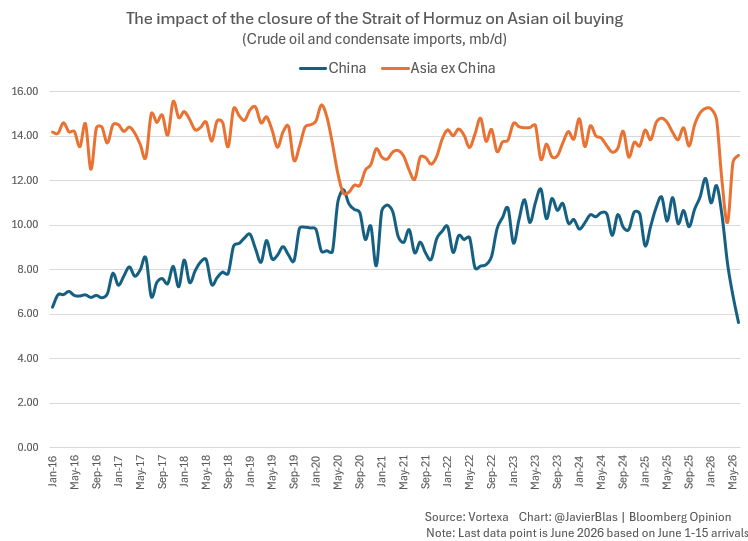
Without strong Chinese demand, fewer barrels are being pulled from the global market, helping keep the system less stressed despite the supply disruptions.
Washington may be able to influence physical security and strategic supply, but Chinese demand is the one major variable the US cannot directly control.
Tool 1: The Reserve Is Meant To Be Refilled, Not Drained
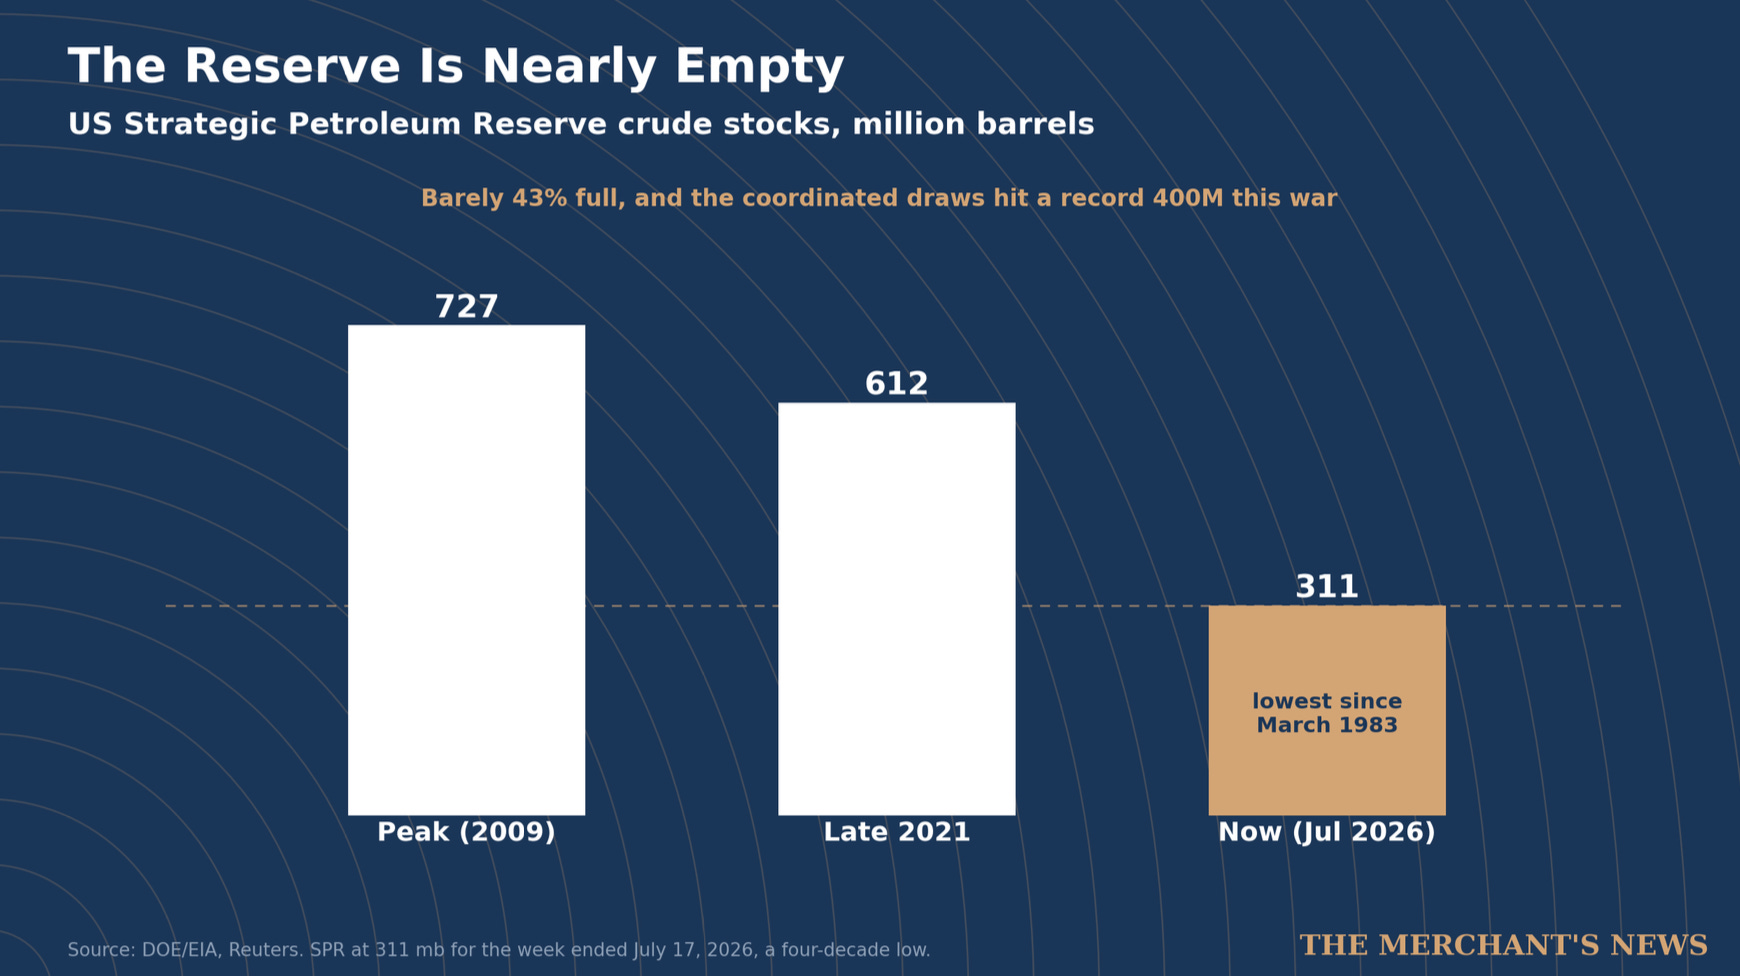
The strategic reserve lever worked because there was always more to release. In the 2022 Russia shock, IEA members agreed a 120 million barrel release and the US pledged another 180 million from its own reserve, roughly 240 million barrels thrown at the market over six months.
This war forced a far bigger draw, a coordinated record of about 400 million barrels, with the US share near 172 million. Each crisis has needed a bigger number, and there is no bigger number left.
The proof is in the tank.
The US Strategic Petroleum Reserve now holds about 311 million barrels, the lowest since March 1983, down from roughly 612 million in late 2021 and a peak near 727 million. Against a design capacity around 714 to 727 million, it is barely 43% full. The job in front of these governments is to buy barrels back, not sell more.
A tool you have to refill is not a tool you can fire.
Tool 2: Russia Can’t Be The Valve Anymore
The second lever was sanctions enforcement, and it was subtler than people remember. Through the spring, the US Treasury issued a series of temporary General Licenses that let Russian crude already loaded and sitting at sea clear and get financed, even while Russian exports were formally under sanction and the G7 price cap.
The Treasury Secretary went further in public, floating that Washington “may lift sanctions on other Russian oil” to ease the tightness. That was the relief valve, not a formal change to the cap but a waiver that kept Russian barrels moving.
That window ran from early March to about mid-June, across several overlapping 30 day licenses.
It has now lapsed.
The last extension was not renewed, the European Commission pushed the coalition back to strict enforcement, and the cap was frozen at $44.10 rather than allowed to drift higher. On top of the policy reversal, Ukraine’s sustained strikes are degrading Russia’s own refining and export machine.
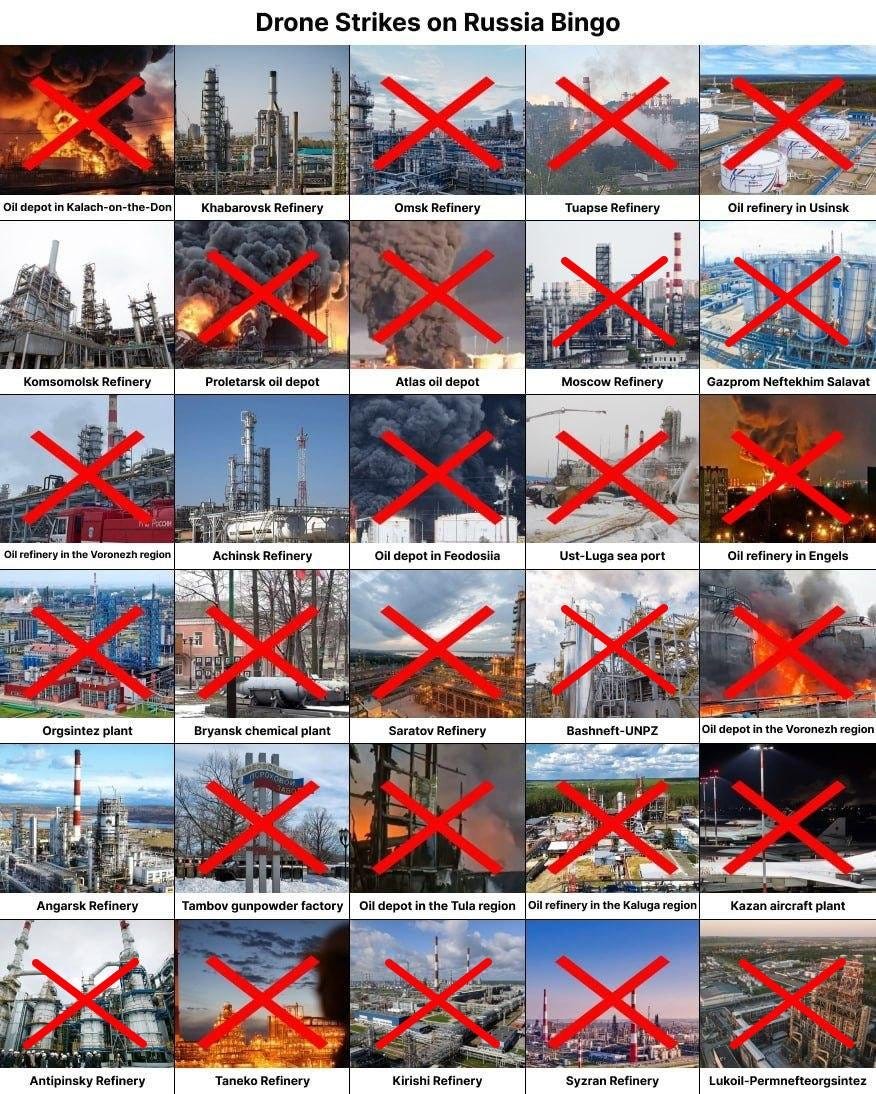
So even if Washington wanted to reopen the valve, both the barrels and the enforcement now point the other way, the valve is shut.
So here is the question that actually matters now when almost nothing can force the price back down except for another MOU or a peace, who owns the barrels the world can’t live without?
Below, I go deep on the one company I think is built for exactly this moment, a producer sitting on safe, export ready oil with a growth runway most of the market is still sleeping on.
I will take its Q2 print apart line by line to see how healthy the business really is, and map out where it goes from here.
Let's dig in👇
